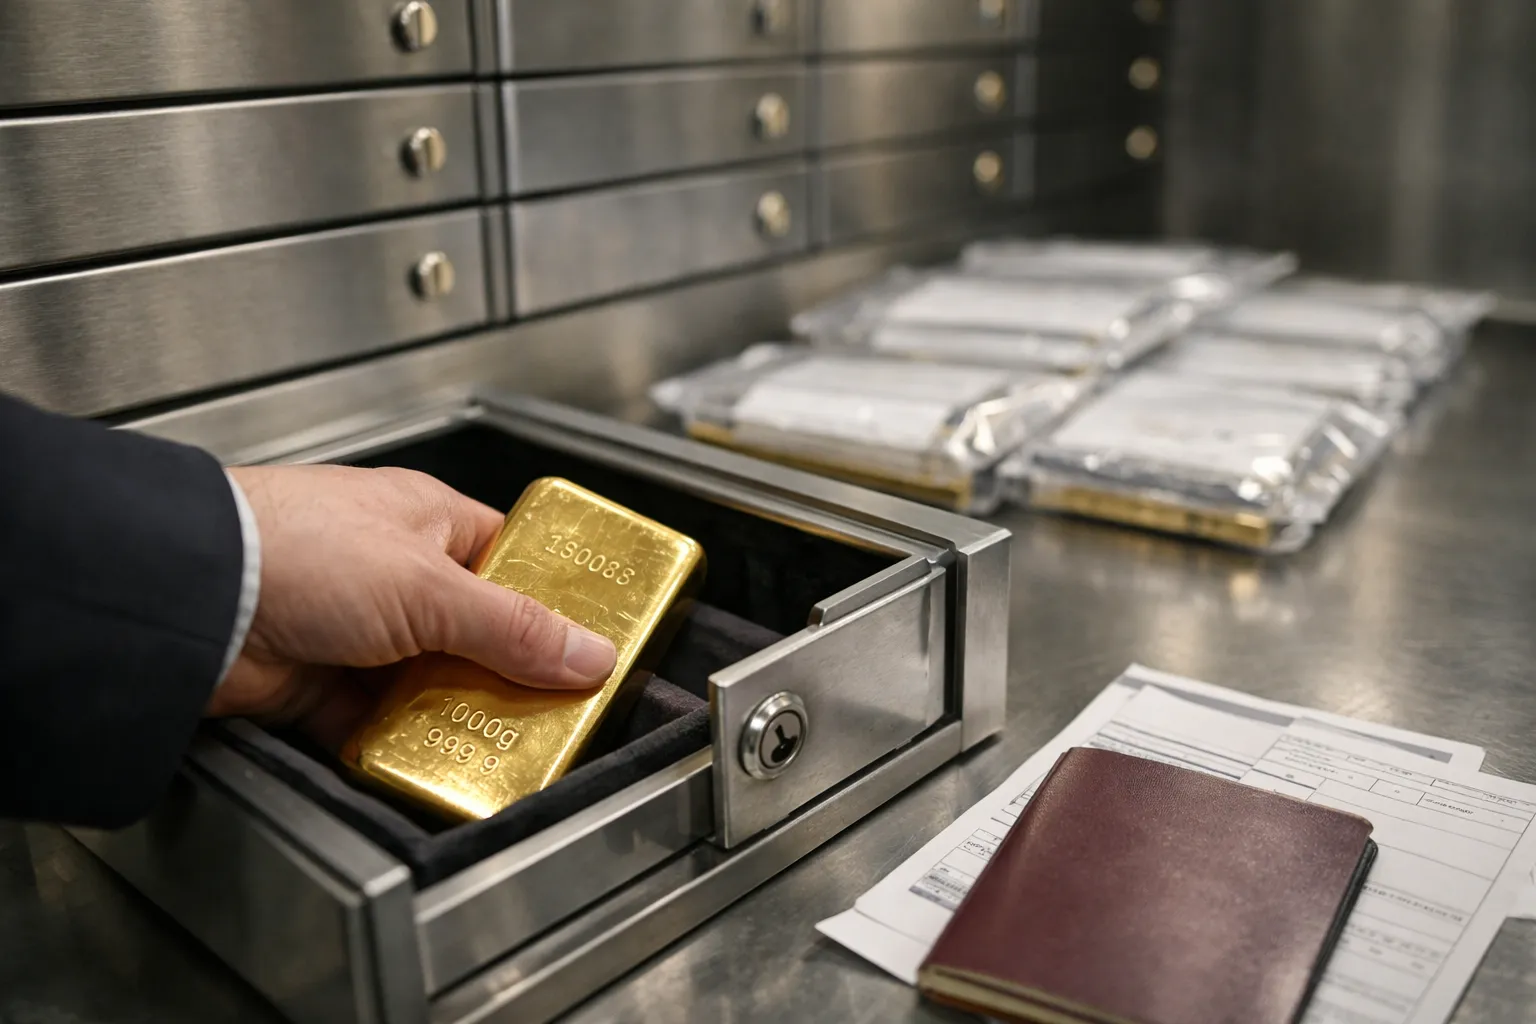
This updated October 2026 guide shows exactly what gold investors must do now to hold physical bullion across borders legally and cost‑effectively. It is written for individual and family investors who already hold or plan to hold bullion outside their country of residence and want concrete, verifiable steps to reduce legal, tax and operational risk. Updates since June 2026 cover regulatory scrutiny of tokenised gold, evolving AML/tax reporting practice, insurance and freight trends, and fresh operational best practices tailored to today's market.
Prerequisites / Context
Before you act, have these three items ready:
- Tax adviser and international counsel: a short written memo from an adviser who understands cross‑border asset reporting for your tax residence and how that interacts with any planned custody jurisdiction.
- Up‑to‑date identification and source‑of‑fund documents: recent passport, proof of address, and original purchase invoices or bank transfer records; expect custodians to request certified copies and to retain them under AML rules longer than before.
- Clear investment policy: a one‑page statement (objective, liquidity needs, access preferences, risk tolerance) that will drive jurisdiction, custody model and documentation requirements.
Why cross‑border gold ownership matters in October 2026
Regulatory and market conditions have continued to tighten in 2026. Key trends to note:
- Enforcement of anti‑money‑laundering (AML) and foreign asset reporting has increased — custodians now operate under stricter KYC and screening regimes and routinely share data with tax authorities where required.
- Tokenisation of bullion matured from pilot projects into live offerings. Some platforms now provide tokens backed by serialised, segregated bars; others remain contractual claims on pooled metal. Regulators and advisers are insisting on written legal opinions proving title and custody arrangements for token products.
- Insurers and freight operators have tightened policy wordings and capacity after several high‑value claims in recent years; clients face narrower per‑item limits and more exclusions (route‑specific, geopolitical, or terror/war risks).
- Major vault hubs — Switzerland, Singapore, Dubai, London, Amsterdam and Frankfurt — remain important, but national AML regimes and domestic reporting obligations have reduced the "privacy" advantage once associated with some locations.
Why this matters: paperwork and contractual clarity now determine whether a cross‑border holding is legally strong or a costly compliance exposure. The practical difference is documentation—signed custody agreements, serialised receipts, insurance wordings and a tax memo.
Overview: the seven essential steps
- Define precise goals and constraints
- Map tax, VAT/GST and reporting obligations
- Choose jurisdiction and custodian type
- Select ownership vehicle and document title
- Arrange insured transport and bonded storage
- Comply with reporting and audit routines
- Plan exit, repatriation and estate succession
Step 1 — Define goals, liquidity needs and risk tolerance
Create a one‑page investment policy that answers:
- Do you require same‑day or on‑demand physical access, or is remote liquidity via trusted dealers/exchanges sufficient?
- Is the holding a long‑term store of capital, a currency hedge, or inventory for trading?
- Which taxes matter for you (VAT/GST at purchase/import, capital gains, wealth or inheritance taxes) and what reporting burden are you prepared to accept?
- Do you need legal title in your name or is a trust/company/nominee preferable for privacy and succession?
- What counterparty risk level do you accept: fully allocated/segregated, pooled allocated, or unallocated?
Why: these answers determine your custody model, which vaults are practical, and the legal paperwork you must insist on. Example: if you need physical access while travelling in SE Asia, Singapore or Dubai vaults with fast delivery windows make more sense than a remote European vault.
Step 2 — Map taxes, VAT/GST and reporting obligations
Tax and reporting errors cause the biggest losses. Updated checks for Oct 2026:
- VAT/GST: regimes still vary by product, purity and import status. Bonded storage remains the primary method to defer VAT on import; verify in writing with customs and the bonded warehouse operator prior to shipment.
- Income, capital gains and wealth taxes: determine whether disposals are taxed in your residence and whether the ownership vehicle (company, trust) triggers CFC or anti‑avoidance rules.
- Foreign account reporting: custodial holdings in foreign vaults are often reportable under national rules, FBAR/FATCA for US persons, and CRS‑based reporting in many OECD jurisdictions. Treat custodial receipts as reportable financial accounts until counsel says otherwise.
- Tokenised products: if you consider tokenised gold, get a written legal opinion confirming whether the token confers legal title to specific metal and whether that metal is held in a custodial account treated as a reportable asset.
- Sanctions and export controls: custodians now use automated screening and provenance analytics; funds with unclear provenance or links to sanctioned jurisdictions may be refused or frozen.
Actionable step: obtain a written tax memo listing VAT/GST treatment, capital gains exposures, and foreign asset reporting obligations for your residence and for the custody jurisdiction.
Step 3 — Choose jurisdiction and custodian type
Consider legal protections, operational reliability and tax consequences. Updated considerations:
- Does local law recognise segregated ownership and protect it in insolvency? Ask for statutory references or precedent.
- Has the custodian published a current ISAE 3402 (or equivalent) report and an independent inventory reconciliation? Demand the latest reports and ask about scope limitations.
- Is the vault integrated with national customs systems for bonded storage and rapid export documentation?
- Does the custodian support verified provenance or blockchain‑backed provenance records, and if so, do those records map to physical serial numbers?
Custody models and trade‑offs remain consistent:
- Allocated, segregated storage: serialised bars/coins under your legal title — best protection, higher cost.
- Allocated, pooled (census): identified in the facility records but stored in pooled stacks — compromise on cost and legal clarity.
- Unallocated accounts: contractual claim on a pool — lowest cost, higher credit exposure.
Actionable step: request custody agreement, ISAE 3402 scope and report, insurance schedule (wording), segregation policy, and any sub‑custody arrangements before transfer. Store these documents in an encrypted file.
Step 4 — Select ownership vehicle and document title
Ownership structure choices affect tax, reporting and succession. Typical options with updated notes:
- Direct ownership: straightforward but transparent; expect reporting. Best for smaller holdings where administrative cost of structures outweighs benefits.
- Family holding company or discretionary trust: useful for succession, but expect CFC/anti‑avoidance scrutiny and additional reporting in many jurisdictions.
- Nominee arrangements: increase complexity — ensure robust nominee agreements that clearly define voting/transfer authority and dispute remedies.
Document checklist (mandatory before transfer):
- Original purchase invoice and assay/certificate
- Vault receipt stating allocated/segregated status and serial numbers
- Signed custody/bailment agreement and full insurance policy wording
- Proof of identity and source‑of‑fund documentation
- Bonded‑warehouse or customs documentation if shipped under bond
Why: in an audit or dispute, serialised vault receipts and custody agreements are the legal evidence of ownership and remedies.
Step 5 — Insured transport, bonded storage and VAT timing
Transport and customs remain risk points. Updated best practices for Oct 2026:
- Use specialist bullion shippers that provide declared‑value insurance with named insurers and published wordings. Insurers now often cap single‑item exposure; request confirmation of per‑item limits and exclusions in writing.
- Prefer direct delivery into a bonded warehouse if VAT/GST is a concern; confirm customs acceptance and bonded receipt procedures in writing before payment.
- Keep a complete chain‑of‑custody file: purchase invoices, shipping AWBs, customs entries, bonded receipts and vault receipts.
- For large holdings, stagger shipments and maintain multi‑route logistics plans to avoid single‑point transit risk.
Actionable step: obtain written confirmation from the receiving vault (with serial numbers) that it will accept and book in the shipment before releasing funds to the seller, and get quotes from at least two bullion logistics specialists.
Step 6 — Reporting, audits and ongoing compliance
Implement annual and event‑driven controls:
- Maintain an encrypted central file with custody agreements, serialised receipts, assay certificates and insurance policy wordings.
- Obtain annual independent reconciliation evidence from your custodian and schedule an independent physical inspection at least every 3–5 years for material holdings.
- Set calendar reminders for foreign asset reporting deadlines and custody/insurance renewal dates.
- If you change tax residence, obtain a written exit opinion from counsel to assess deemed disposal, exit tax or registration requirements.
Actionable step: produce a one‑page holdings summary (jurisdiction, custodian, serial numbers, acquisition cost, purchase date, insurance limits) and store a copy with your estate documents and a trusted adviser.
Step 7 — Plan the exit: repatriation, sale and succession
Plan exits early; late decisions are costly:
- Decide whether to sell locally or repatriate physically — selling in‑jurisdiction avoids freight but may create local tax exposure.
- Preserve original purchase documents and customs records to prove acquisition cost and VAT treatment.
- Include vault access instructions, custodian contact and a copy of the custody agreement in your estate plan to avoid executor delays.
Actionable step: create an "exit playbook" listing preferred buyers, pre‑approved shipping routes, trusted customs brokers and a timeline to sell or repatriate within an acceptable window.
Practical cost benchmarks (October 2026 typical ranges)
Use these directional ranges when comparing offers; obtain written rate cards:
- Premiums over spot at purchase: 0.6–4.0% for standard bars (1oz–1kg); 1–7% for commonly traded coins depending on rarity and demand.
- Allocated, segregated vaulting fees: 0.12–0.9% p.a. of value (retail minimums higher for under‑1kg lots; institutional scales lower).
- Unallocated metal accounts: typically a small basis‑point fee or monthly charge, but with counterparty credit exposure.
- Shipping and insured transport: $150–$900 per shipment depending on size, route and declared value; high‑security escorted shipments cost more.
These ranges are indicative. Always request full written quotations including VAT/GST, customs handling and exit fees.
Red flags and questions to ask every custodian (Oct 2026 checklist)
- Can you inspect serial numbers and request physical verification on demand? If not, why?
- Is storage allocated and segregated in law, not only in ledger entries? Ask for legal references and insolvency protections.
- Can metal be rehypothecated, lent or used in derivative books? Are there limits and notice periods?
- Who is the insurer, what are per‑item limits, and can you review the full insurance policy wording (including war/terrorism exclusions)?
- Do you publish an ISAE 3402 (or equivalent) report and independent inventory reconciliations? Request the latest copies.
- What is the documented process and timeline for physical delivery or sale, and what fees apply on exit?
- Do you conduct enhanced sanctions and provenance screening, and could that screening block or delay transfers?
Case example — updated October 2026
Investor C is a US citizen resident in Dubai who wants to hold 10kg of 1kg bars as a long‑term hedge and to retain local access while travelling. Steps taken:
- Tax and reporting: obtains a written memo from US tax counsel confirming FBAR/FATCA implications of holding a custodial account abroad and the reporting treatment under UAE rules (UAE has no personal income tax but custodial accounts may still be reportable to the US).
- Custody selection: asks three Dubai and two Swiss vaults for ISAE 3402 reports, full insurance wordings, and a segregation policy; chooses a segregated, allocated account in Dubai with a published independent inventory reconciliation and a 10‑business‑day delivery promise.
- Transport: uses two separate bullion logistics firms to compare coverage and route risk, ships in two tranches into bonded storage to preserve VAT position for any future re‑export.
- Tokenisation caution: declines a tokenised‑gold platform that could not deliver a written legal opinion that the token confers title to specific, serialised bars held in segregated custody.
- Ongoing compliance: retains copies of signed custody and transport agreements in an encrypted vault, sets annual reminders for independent reconciliation and FBAR/FATCA filing deadlines.
Common mistakes to avoid
- Accepting verbal custody terms — always obtain signed agreements and serialised receipts.
- Assuming tokenised gold equals allocated physical metal — verify legal title and custody arrangements in writing.
- Failing to obtain and review insurance policy wordings and auditor reports — both are essential for claims or disputes.
- Not planning for sanctions or AML screening delays — expect hold‑ups and document contingency plans.
- Ignoring an exit playbook — lack of planning often causes high shipping costs and unexpected tax outcomes when liquidity is needed.
Pro tips
- Split holdings across two jurisdictions to reduce operational and political risk and to maintain local access in emergencies.
- Stagger purchases to reduce market and transit concentration risk; maintain a rolling insurance and shipping plan.
- Negotiate a capped exit fee or a delivery timeline in the custody agreement to avoid open‑ended costs on sale or delivery.
- For tokenised gold, insist on contract language that ties each token to specific serialised bars and on the custodian’s audit confirming that mapping.
- Keep a short, plain‑language “executor brief” explaining vault access, custody contact, and required documents — store it with estate papers and an encrypted copy with a trusted adviser.
FAQ
Do I have to report bullion held in a foreign vault to my home tax authority?
Often yes. Many countries require disclosure of foreign custodial holdings even if the metal is physically abroad. US persons must consider FBAR/FATCA and Form 8938 thresholds; many OECD countries treat custodial accounts as reportable under CRS. Obtain a short written tax memo for your specific residence to confirm which forms and thresholds apply.
Is tokenised gold the same as owning allocated physical bullion?
Not necessarily. Tokenised gold can mean (a) a token representing a specific serialised bar held in segregated custody, (b) a token representing a share of pooled physical metal, or (c) a contractual claim with no underlying physical commitment. Ask for a written legal opinion and see contractual evidence that tokens map to serial numbers and segregated custody if you want true physical backing.
Can I avoid VAT by storing gold in a bonded warehouse?
Often yes, for imports and re‑exports: bonded storage defers VAT/GST until the metal is removed for domestic consumption. Whether VAT is avoided entirely depends on intended use (re‑export vs local sale) and local customs rules. Get written confirmation from customs, the bonded warehouse and your tax adviser before relying on this treatment.
What changed about insurance and shipping in 2026 that I should know?
Insurers tightened policy wordings and per‑item limits after a spate of high‑value claims; some routes and geopolitical exposures have explicit exclusions. Freight operators increased scrutiny and demand more provenance paperwork. Always obtain and review full policy wordings and confirm per‑item limits, territorial and war/terrorism exclusions in writing before transfer.
How often should I physically verify serial numbers?
At minimum, obtain an independent inventory reconciliation annually. For larger holdings or higher operational risk, schedule a physical verification every 2–3 years performed by an independent professional. Ensure custodians’ audit reports are reviewed annually as part of your compliance routine.
Final checklist — what to have in place before you transfer gold abroad
- Written tax opinion covering VAT/GST and foreign asset reporting for your residence
- Signed custody/bailment agreement and serialised vault receipt
- Full insurance policy wording showing coverage limits, exclusions and per‑item caps
- Documented shipping contract with a specialist bullion carrier and sample airway bill
- Exit playbook: preferred buyers, repatriation routes, customs broker contact and timelines
- Succession instructions and a one‑page holdings summary for your executor
Cross‑border gold ownership in October 2026 still rewards careful preparation: define objectives, document ownership clearly, choose reputable custodians with independent audits, keep tidy reco