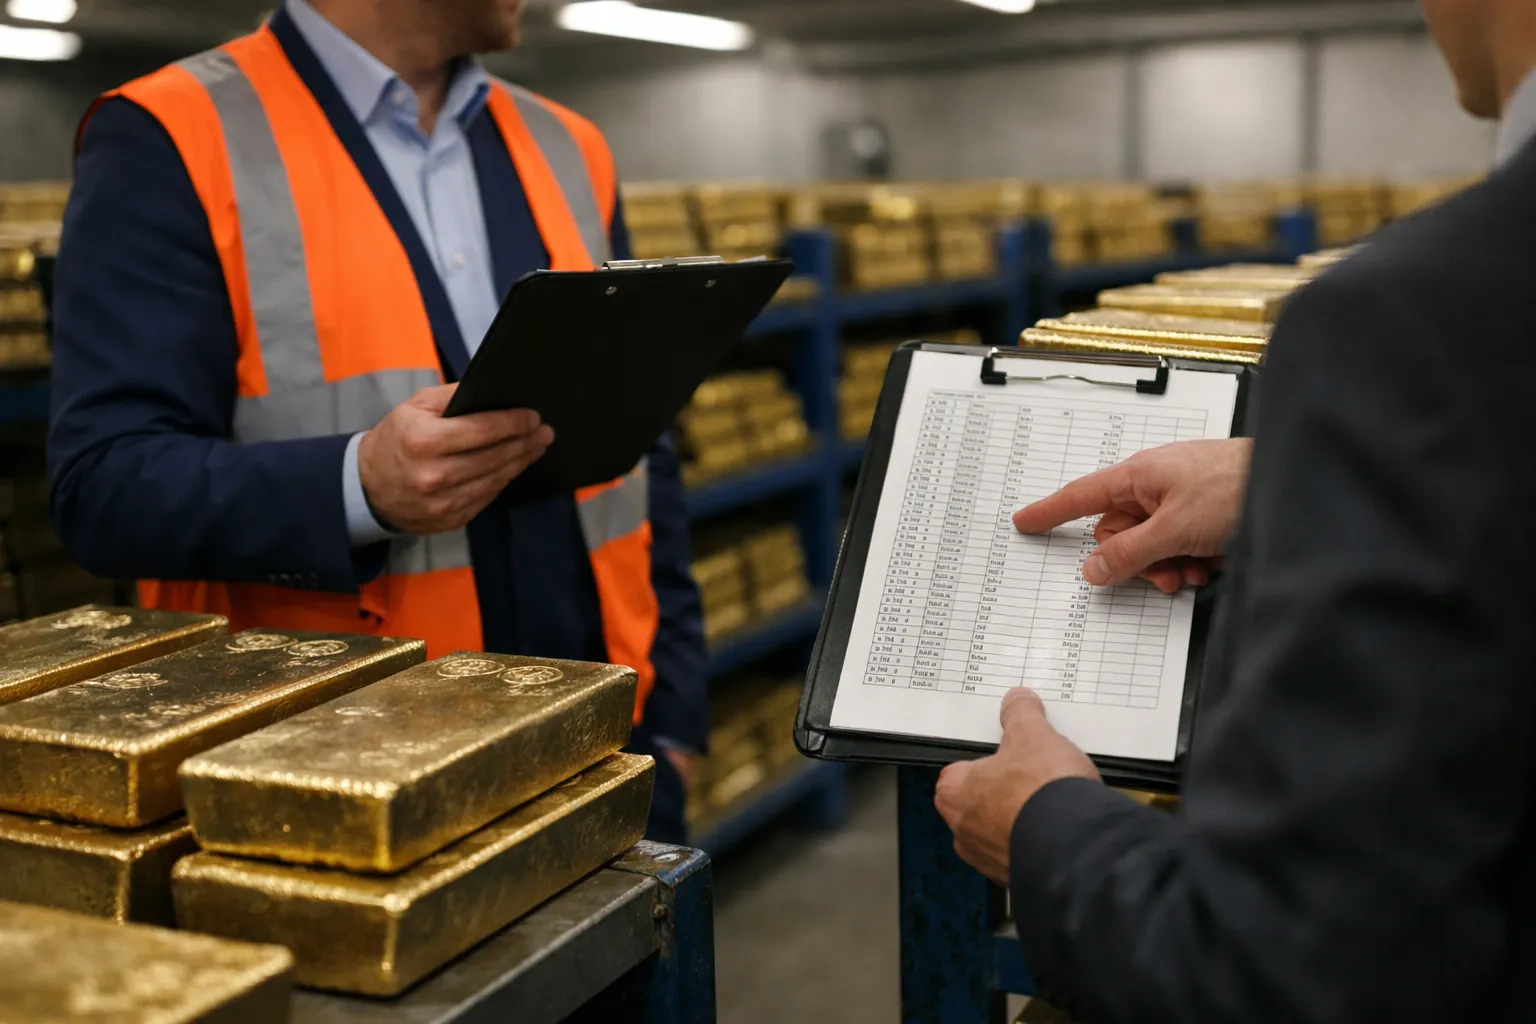
London, June 18, 2026 — Who: the World Gold Council (WGC) and a group of London bullion‑market participants. What: an ongoing pilot to test same‑day (T+0) settlement and bar‑level tokenization for LBMA Good Delivery gold. When: pilot launched Feb. 2, 2026 and entered an extended testing phase through mid‑2026. Where: London vaults and market infrastructure, using custodian networks including Brink’s, Loomis and Malca‑Amit. Why it matters: if the pilot delivers repeatable T+0 workflows and reliable bar‑level reporting, tokenized gold could lower settlement risk, compress spreads and force products to compete on transparent total cost rather than marketing claims.
Why this matters in June 2026
Tokenized gold is selling an operational upgrade: faster settlement and clearer provenance. But the numbers tell a different story. Headline fee claims are only one piece of total cost. Investors must quantify: expected round‑trip spread + custody/mint‑burn fees + redemption economics + operational failure rates. For baseline comparison, the big physically backed ETFs remain cheap on visible fees: SPDR Gold Shares (GLD) lists a 0.40% annual expense ratio and iShares Gold Trust (IAU) 0.25%.
Since March, pilot participants have increasingly focused on producing the precise metrics that let investors compare token products to ETFs. That shift matters because retail and adviser demand will hinge on verifiable, historical data — not promotional brochures.
What the pilot is testing — and new things to measure in June 2026
The pilot’s core tests remain T+0 settlement, bar‑level linkage, standardized reporting and mint/burn controls. For investors evaluating token platforms now, ask for these concrete, date‑stamped metrics (preferably covering the most recent 90 days):
- Settlement success rate: Target is 95%+ same‑day settlement without manual remediation. Pilot participants we spoke with reported interim success rates clustering between 90%–97% in May 2026; persistent readings below 90% indicate operational immaturity.
- Reconciliation latency: Bar‑list and vault reconciliation within 24 hours is a reasonable minimum; sub‑4‑hour reconciliation is demonstrably stronger for intraday confidence.
- Spread benchmarks: For tokens to be competitive with ETFs, liquid bid/ask spreads should compress below 10 basis points (0.10%). Pilot trading in London hours has shown mid‑day liquidity with spreads often in the 10–25 bps range for retail‑sized trades and wider off‑hours; ask for trade‑size buckets (1 oz, 10 oz, 100 oz) rather than a single headline figure.
- Redemption mechanics: Minimum physical redemption sizes, fees and lead times determine whether a token is materially deliverable. Many issuers in testing still require high minimums (100–400 oz) for physical delivery; a handful now provide sub‑1‑oz cash‑out or small physical redemption routes — get specifics and sample invoices.
- Audit and proof‑of‑reserves: Daily or near‑daily bar lists with refiner, serial number, weight and custodian location, plus a named independent auditor and published exception reports, are the gold standard.
Context: why T+0 across London’s market plumbing is non‑trivial
London’s OTC bullion market is built on LBMA Good Delivery conventions, bespoke custody contracts and manual workflows. Synchronizing trading venues, custodial APIs, issuer keys and legal title transfer so that tokens map to identifiable bars — not pooled claims — requires both technical integration and contractual clarity. That friction explains why many pilots still see occasional manual interventions and why settlement success rates under 95% are common during stress testing.
Details investors should demand now
When assessing token products, read the fine print and ask for documentary proof. Here’s an updated due‑diligence list that goes beyond marketing copy:
- Title and allocation: Is title to specific allocated bars transferred on settlement, or are tokenholders a pro‑rata claimant on pooled metal? Demand the legal opinion documenting title transfer mechanics.
- Bar list transparency: Daily publication of refiner, serial number, weight and vault location; ideally with time‑stamp and hash‑signed file to prevent retroactive edits.
- Named auditors and methodology: Look for auditors that publish testing methodology and exception reports; "third‑party audit" without names is not sufficient.
- Insolvency treatment: Confirm whether metal sits in bankruptcy‑remote trust or is subject to the issuer’s estate. Ask for the custody contract and any published legal opinions on estate ring‑fencing.
- Redemption economics: Request actual recent invoices for physical redemptions and cash‑outs, including fees and lead times — not theoretical schedules.
Practical impact: costs, liquidity and where tokens can win
If the pilot achieves reliable T+0 with transparent bar linkage, tokenized gold could compress spreads and lower effective round‑trip costs — but only if two other ingredients arrive: market makers willing to commit inventory and clear, low‑friction redemption mechanics. Market makers need balance‑sheet financing and predictable legal title transfer; custodians and issuers must make metal moveable without entangling it in issuer insolvency.
Rule of thumb for investors: compare total cost for your trade size and frequency. If a token shows an average spread of 30 basis points for your typical trade while GLD’s intra‑day spread remains 3–7 bps, the ETF will likely be cheaper overall despite a higher expense ratio. Ask issuers for anonymized trade‑level spread data over the last 90 days and convert round‑trip spreads into an annualized cost based on your expected turnover.
Reactions and industry signals
World Gold Council — in its Feb. 2, 2026 announcement — said the pilot aims to "strengthen confidence and transparency" in digitally represented gold. Pilot participants have told Gold Investment News they are prioritizing auditable bar‑lists and settlement SLAs to provide that confidence.
Custodians and market participants welcome standardization but caution that successful operational testing does not equal regulatory approval. A senior operations executive at a major London custodian, speaking on background, told Gold Investment News that "technical success must be matched with legal certainty — otherwise tokenized workflows substitute one set of risks for another." That caution reflects ongoing conversations with UK and EU authorities over safeguarding and insolvency treatment; regulatory clarity remains an open variable through the rest of 2026.
Actionable checklist for gold investors (June 2026)
- Request 90‑day quantitative metrics: average spread by trade size, settlement success rate, reconciliation latency and number of manual interventions.
- Inspect legal documents: confirm allocated title, named custodian, bar‑list frequency and insolvency protections — get legal opinions where available.
- Compare total cost: annualize round‑trip spread for your turnover and add custody/management and mint/redemption fees. Use GLD (0.40%) and IAU (0.25%) as baseline comparators.
- Verify redemptions: request a recent physical redemption or cash‑out invoice and expected lead times; if the minimum is hundreds of ounces, treat the product as effectively non‑deliverable for most retail investors.
- Demand named audits: daily bar lists, named auditors and published exception reports — vague "third‑party audit" statements are insufficient.
What’s next — what to watch through late 2026
- Final pilot report or published operational standards from the WGC or pilot participants (timing expected later in 2026).
- Evidence of major market‑maker commitments in London liquidity pools — that would materially tighten spreads.
- Regulatory guidance from UK or EU authorities on safeguarding and insolvency treatment for tokenized commodities; such guidance will reshape custody models.
- Platform rollouts that move from institutional‑only pilots to retail‑facing products with verifiable small‑redemption paths.
FAQ
Is tokenized gold the same as owning physical gold?
Not automatically. Only tokens backed by allocated title to specific bars with clear custody and insolvency protections replicate physical ownership. The numbers matter: check bar‑list frequency, named custodian and legal treatment of the metal in insolvency.
Does T+0 settlement remove investment risk?
No. T+0 reduces settlement and intraday counterparty exposure, but it does not remove custody risk, issuer risk or legal risk. You still need to verify where the metal sits and how claims are enforced in insolvency.
How should I compare costs between tokens and ETFs?
Compare total cost: expected round‑trip spread (annualized based on your turnover) + custody/management fees + mint/redemption charges. ETFs’ expense ratios (GLD 0.40%, IAU 0.25%) are transparent; tokens require documented spread histories and concrete redemption invoices to be comparable.
What minimums make a token “deliverable” for retail investors?
If minimum physical redemption is in the hundreds of ounces (e.g., ~400 oz LBMA bars), the token is practically non‑deliverable for most retail investors. Look for products that enable small redemptions or straightforward cash‑outs with published, recent invoices.