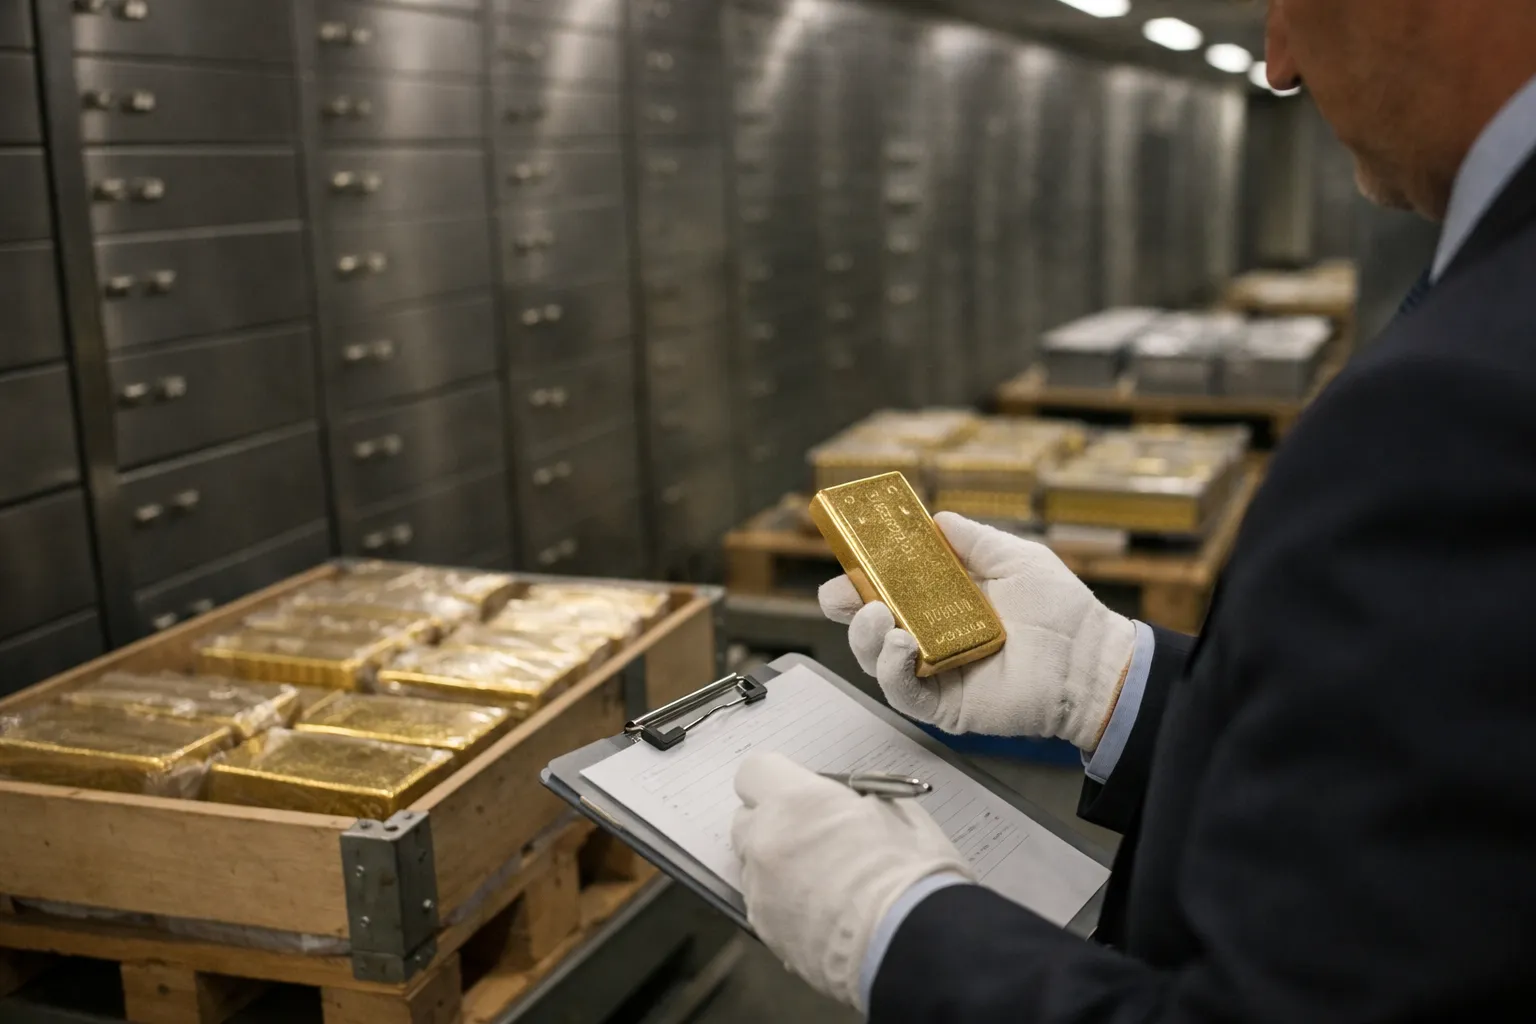
As investors increase allocations to physical gold, selecting the right international vault has moved from an operational detail into a strategic decision. Since 2022 demand for offshore storage grew with capital flows and geopolitical uncertainty; by 2026 investors care as much about insurance wording, repatriation mechanics and auditability as they do about vault fees.
This guide walks gold investors through a focused, practical 10-step process to evaluate and choose an insured international gold vault. Each step explains what to ask, what documents to obtain, and how to benchmark providers so you can make a defensible, auditable choice.
Step 1 — Clarify your custody goals and constraints
Begin by defining what you need from a vault. Common differentiators:
- Allocated vs unallocated storage (full ownership and serial-numbered segregation versus creditor-backed balance)
- Short-term trading access vs long-term strategic storage
- Need for repatriation or cross-border transfer rights
- Tolerance for jurisdictional or sanction risk
- Minimum bar sizes or coin types you will store (LGD bars, kilobars, sovereign coins)
Document these constraints up front — they direct jurisdiction choice, insurance requirements and contractual terms.
Step 2 — Narrow jurisdictions with a sovereign-risk filter
Vault location matters. Use a three-factor filter:
- Legal stability and property-rights record: how reliable are private-property protections and how frequently have vaults been subject to freezes or requisitions?
- Sanctions exposure: is the jurisdiction likely to be targeted by sanctions regimes or financial restrictions that could impede access?
- Regulatory oversight and market infrastructure: presence of established bullion markets (e.g., London, Zurich, Singapore, Dubai) and recognized customs and banking processes.
Shortlist two or three jurisdictions that match your risk tolerance. For many private investors in 2026, Switzerland, Singapore, the UAE (Dubai), the UK (London) and certain EU hubs remain common choices; each has different strengths on legal comfort, tax treatment and logistics.
Step 3 — Allocated vs pooled: insist on how segregation is implemented
“Allocated” is not a marketing label — verify the mechanics:
- Serial-numbered segregation: bars/coins should be identifiable by serial numbers on your inventory records and, ideally, physically separated behind a dedicated locker or box.
- Direct title: your name or legal entity should appear as the owner on custody documents; avoid arrangements where the custodian's balance sheet claims legal ownership.
- Proof of immediate physical access: confirm processes for inspection, and whether the vault allows independent, unscheduled audits.
If you require fungible pooling for cost reasons, understand the counterparty-credit risk and the remedies available if the custodian becomes insolvent.
Step 4 — Audit the insurance policy, not just the premium
Insurance is the single most important protective layer. Get a full copy of the insurer’s policy and have a specialist (broker or legal counsel) review it. Key clauses to check:
- Insurer identity and rating: top-tier policies are often underwritten by Lloyd’s syndicates or A‑rated global carriers; ask for the exact insurer name and policy number.
- Coverage basis: “all-risks” vs named perils. All-risks is broader; named-perils can exclude theft or certain loss modes.
- Policy limits and per-item caps: confirm whether the policy covers full replacement value per bar or imposes sub-limits.
- War, nuclear, cyber and sanctions exclusions: many policies exclude losses caused by war or by sanctions-related government actions — decide if you can accept those exclusions.
- Deductible and coinsurance terms: operational losses sometimes carry significant deductibles; quantify net recoverable amounts.
- Subrogation and third-party recovery: ensure you are not contractually prevented from pursuing recoveries.
- Notification and claim timing: understand how fast claims are processed and what documentation the custodian must provide.
Do not accept insurance summaries. Obtain the full policy wording and an insurer confirmation letter that names the vault and scope of cover for your holdings.
Step 5 — Confirm reporting cadence and audit access
Reliable reporting is essential for control and compliance:
- Inventory statements: request weekly or monthly statements that include serial numbers, weights, fineness, and movement history.
- Independent audits: ask whether the vault undergoes annual third-party audits (name the auditor — e.g., Big Four firms) and request the latest audit report or certificate.
- On-demand inspections: negotiate at least one right of independent on-site inspection per year without advance notice.
Step 6 — Examine transport, chain-of-custody and transfer mechanics
How your metal moves matters as much as where it sits:
- Approved carriers: insist on armored transport providers with verifiable track records and separate insurance during transit.
- Customs and export controls: confirm the vault’s experience handling export/import paperwork for your home jurisdiction and whether temporary admission mechanisms apply.
- Delivery timelines: obtain contractual timeframes for release and shipment (e.g., 5–15 business days) and escalation paths for urgent repatriation.
Step 7 — Benchmark total cost of ownership
Vault fees are visible, but total cost includes transport, insurance loadings, audit fees, and exit charges. To benchmark:
- Request an itemized quote for your exact holdings profile (bar sizes, coins, weight).
- Include inbound and outbound transport, handling, certificate issuance and VAT or customs duties where applicable.
- Calculate annualized percentage cost: total annual fees divided by metal value; compare multiple providers on this basis.
Example factors that drive price differences: storage tier (allocated individual locker vs pooled), bar size (LGD bars cheaper per oz), jurisdictional tax and VAT handling, and insured limits.
Step 8 — Negotiate contractual protections
Standard custodian contracts are written in the custodian’s favor. Negotiate where possible:
- Audit and inspection rights (unscheduled)
- Specific insurance naming: insurer must confirm policy covers your holdings and commit to notify you of any material changes
- Repatriation SLAs and remedies for missed delivery
- Dispute-resolution forum (neutral arbitration seat, governing law)
- Assignment and succession clauses to protect you if the custodian is sold
Small changes — named insurer confirmation, clear SLAs, and an audit clause — materially reduce legal and operational risk.
Step 9 — Verify counterparties and run references
Do background checks:
- Ask for client references (other investors, bullion dealers, banks)
- Check public lists for regulatory actions, litigation or sanctions against the vault operator or insurer
- Confirm vault operator’s balance-sheet strength and parent company guarantees if applicable
Request at least three client references and speak with each about claims experience, responsiveness, and real repatriation cases.
Step 10 — Prepare exit and contingency plans
No vault should be chosen without an exit plan. Document:
- Primary and alternate liquidation routes (custodian sale, auction, local dealer)
- Time-to-cash estimates under normal and stressed conditions
- Repatriation checklist, including customs paperwork, tax implications and transport bookings
- Contingency funding for emergency repatriation or insurance deductibles
Simulate a repatriation exercise with your selected custodian: request a hypothetical timeline and cost for moving full holdings to an address in your home country.
Practical example: working through the process
Say you are a European private investor storing 100 troy ounces in kilo bars for a 3–5 year horizon. Your shortlist might include vaults in Zurich and Singapore. You would:
- Request full insurance wording and a named-insurer confirmation for your holdings.
- Confirm allocated, serial-numbered segregation and monthly audit certificates.
- Get an itemized fee quote (storage, inbound/outbound handling, transport) and compute annualized cost versus alternative vaults.
- Negotiate an unscheduled inspection right and a 7–14 day repatriation SLA for full delivery.
- Run at least three client references and obtain the latest third-party audit report.
Make your decision when contractual protections and operational practices meet your risk tolerance and cost benchmarks.
Red flags to walk away from
- No full insurance policy on request (only summaries provided)
- Unwillingness to provide auditor name or audit reports
- Vague segregation practices or refusal to identify serial numbers
- Sanctions or war exclusions that would likely apply under plausible scenarios
- Excessive unilateral change clauses that allow the custodian to alter terms without your consent
Final checklist — documents to obtain before funding
- Executed custody agreement with negotiated clauses
- Full insurance policy wording and a signed insurer confirmation letter
- Latest independent audit/certification
- Detailed fee schedule and sample invoice
- Transport and repatriation workflow and SLA
- Client reference list and due-diligence notes
Choosing an insured international vault is both a technical procurement exercise and a strategic asset-allocation decision. Investors who follow a methodical, document-driven process — clarifying goals, vetting insurance, checking segregation mechanics, and testing exit routes — significantly lower the odds of surprises during market or geopolitical stress.
In 2026 the market offers more custody choices than ever. With careful due diligence and contractual protections an investor can secure physical gold offshore while retaining transparency, auditability and a clear path to liquidity.