
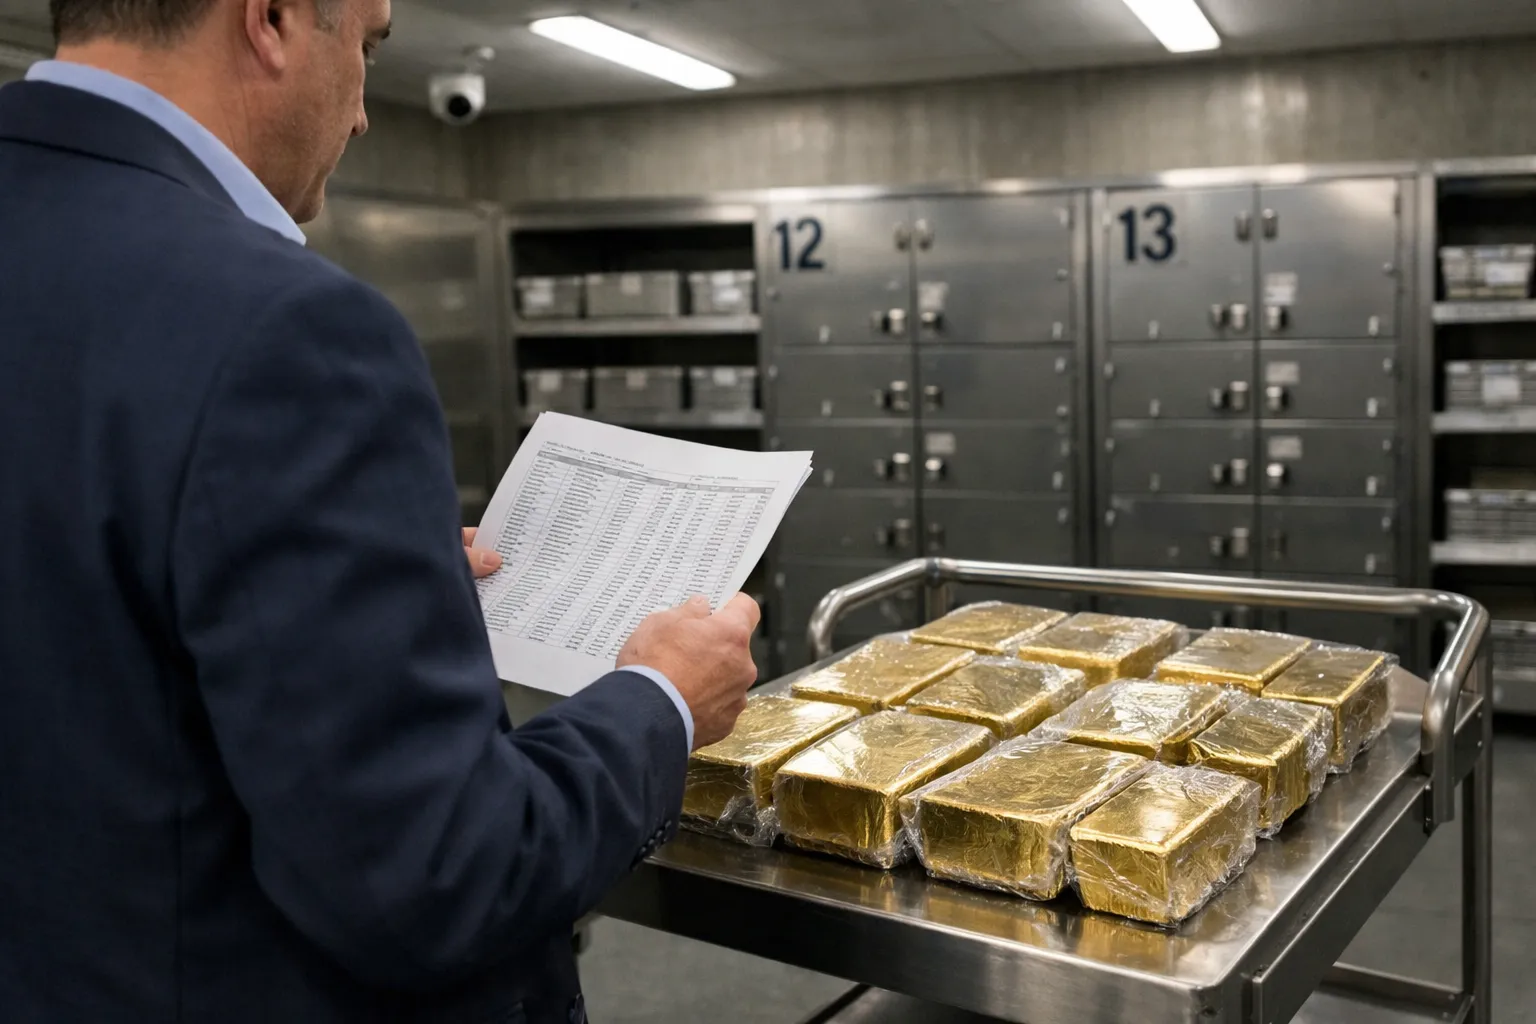
By Sarah Chen, Senior Financial Analyst. This update refreshes our June 2026 guidance with the latest market context and practical checks buyers must run in July 2026. You’ll get the exact verification list to demand, updated cost modeling examples, how recent custody tech changes affect (but do not replace) legal title, and a concise provider scorecard you can use today.
Who this is for and why it matters
This is for retail and semi‑professional investors who want physical exposure to gold without storing metal at home. The numbers tell a different story than marketing: headline “allocated” can mask material legal and cost differences that change outcomes over 1–10 year horizons. Read this before funding any allocated program.
Prerequisites / Context: What “Allocated Gold” Still Means
In plain terms: allocated means the custodian or provider has identified specific bars to your account (serial numbers, refiner, weights). The legal framework is typically bailment—the custodian holds your property rather than owing you a general credit.
Contrast: unallocated is a creditor claim on a pool. In insolvency, creditors’ outcomes depend on contract language and local insolvency law, not on the marketing word “allocated.” That basic legal distinction has not changed in July 2026.
What did change through H1 2026: digital interfaces and tokenized wrappers continued to proliferate. Many platforms now publish more frequent attestations and on‑chain references; some large dealers have trimmed retail buy premiums modestly after expanding scale. But the legal question—do you own specific bars or a claim?—remains the decisive one.
Allocated vs. Segregated vs. Commingled — why the distinction matters now
- Allocated: bars are identified to you (serials/refiner).
- Segregated: your bars are physically separated (higher cost, clearer chain of custody).
- Allocated but commingled: assigned bars may sit next to other allocated bars but remain separately recorded.
Your verification checklist should prioritize (1) legal title language, (2) bar identification and bar lists, (3) custody chain and independence, and (4) independent audits/reconciliations.
Step 1: Decide Your Use Case (This Drives Costs and Structure)
Decide what you’re optimizing for before selecting a provider. Your use case determines acceptable trade‑offs on custody fees, buy/sell spreads, delivery option costs and liquidity.
- Long‑term hold (≥5 years): prioritize low annual custody (target ~0.10%–0.40%/yr for retail allocated) and explicit insolvency protections.
- Medium term hedge (1–5 years): prioritize narrow buy/sell spreads even if custody is higher—this minimizes realized friction.
- Delivery optionality: if you may take physical delivery occasionally, prioritize clear fabrication/withdrawal pricing and minimum sizes; expect materially higher costs for small retail deliveries.
- Jurisdiction diversification: if you want legal diversification, prioritize vault locations and the governing law in the client contract.
Example: On $50,000 of gold, a custody fee gap from 0.20% to 0.60% equals $200/year. Over 10 years that’s $2,000 (ignoring compounding)—often bigger than one‑time premium differences.
Step 2: Verify You’re Getting Specific Bars — Demand a Bar List
Litmus test: before you fund, the provider must produce a current bar list for your account showing:
- Refiner name and assay standard (e.g., LBMA Good Delivery for large bars; .999 for many retail bars)
- Serial numbers
- Gross and fine weight
- Fineness and assay marks
- Vault location and named custodian
If the provider can’t produce a bar list tied to your account immediately, treat the product as functionally unallocated despite marketing. In July 2026 more platforms can produce near‑real‑time bar lists; ask for the latest dated export (PDF or CSV) and compare it to your account statement.
Minimum sizes and their economics
Common bar sizes and typical economics (retail environment mid‑2026):
- 1 oz: buy premium ~2.0%–4.0% (most expensive per ounce for fabrication and distribution)
- 100 g: buy premium ~2.5%–4.5%
- 1 kg: buy premium ~0.8%–1.8%
- Good Delivery (~400 oz): buy premium often below 0.5% but storage/transfer logistics differ
Shipping and insulated insured delivery for small parcels in 2026 typically runs $30–$150 depending on insurer and destination; larger shipments carry different pricing and customs considerations.
Step 3: Read the Custody Contract Like an Analyst (Who Holds Title?)
Contracts are where investors get tripped up. Look for three explicit items:
- Legal title: Does the service agreement state you have beneficial and/or legal title to identified bars?
- Custodian relationship: Is an independent, recognized vault operator the named custodian—ideally with direct contractual obligation to clients?
- Insolvency treatment: Does the agreement say allocated metal is held off the provider’s balance sheet and must be segregated and returned to clients?
Watch for clauses permitting the provider to “use, lease, pledge, substitute or otherwise encumber” metal without requiring client consent. Substitution can be acceptable if constrained and documented; open‑ended rights without notification are a red flag.
Step 4: Demand Controls — Audits, Reconciliations, and Insurance
“Audited” is an overloaded word. Ask explicitly:
- Who performs the audit or attestation, and how often? (annual independent vault audits or semi‑annual attestations are common.)
- Do client statements show bar‑level detail (serials and weights) versus aggregate ounces?
- Insurance details: insurer name, policy limits, per‑client vs blanket coverage, covered perils, and deductible amounts.
Important nuance: insurance typically covers physical loss/theft—not provider fraud or misrepresentation—unless the policy specifically covers those events. If a provider advertises “fully insured,” ask for the insurance schedule and the named insured.
Step 5: Calculate the All‑In Cost — Build a Simple Model
Real return = gold price move – friction. Model the friction explicitly. Create a spreadsheet and fill in line items with provider numbers.
Checklist — put real numbers next to each line:
- Buy premium (% over spot)
- Sell discount / spread (% under spot)
- Annual custody / storage fee (%/year; watch for dollar minimums)
- Account / admin fees (monthly/annual)
- Fabrication / withdrawal fee for delivery
- Shipping & handling (insured shipping costs)
Updated break‑even example (July 2026)
Assume you buy $25,000 of allocated gold and hold 3 years. Updated plausible retail numbers for mid‑2026:
- Buy premium: 1.5% = $375
- Sell spread: 1.0% = $250
- Custody+insurance: 0.40%/year = $100/year
- Withdrawal shipping if delivered: $75 one‑time (assume not taken)
Total friction: $375 + $250 + (3 × $100) = $925 or 3.7% of $25,000. The numbers tell a different story than marketing: custody and spreads often exceed the headline premium over short horizons.
Note on fee minimums: a 0.30% custody fee with a $150 minimum is effectively 3.0% on a $5,000 holding, not 0.30%.
Step 6: Confirm Liquidity and Exit Mechanics
Selling is where hidden costs show up. Ask directly:
- Who bids? Can you sell to third parties or are you limited to the provider?
- How is pricing set? Is it a stated formula (spot ± X bps) or “market at the time” pricing?
- Settlement timeline: same day, T+1, T+3? Longer timelines create timing risk in volatile markets.
- Transfer‑out rules: fees and documentation to move bars to another vault (and realistic lead times).
Real‑world check: some programs advertise low custody rates but widen sell spreads or levy “administration” charges at liquidation. Treat exit costs as core product charges, not optional extras.
Step 7: Provider Risk Scorecard — Make a Quantitative Checklist
Allocated ownership reduces some risks but not provider operational risk. Use a simple scorecard and weight items by importance for your use case. Suggested weighting (example): legal title 30%, custodian independence 20%, audit frequency/transparency 15%, fee economics 15%, jurisdiction 10%, operational history 10%.
- Custodian independence: independent vault vs provider‑operated storage
- Jurisdiction: established custody hubs (London, Zurich, Singapore, Delaware, Singapore) have clearer precedents—choose based on ease of legal recourse and tax implications
- Transparency: are bar lists, audit attestations, and fee schedules published or available on demand?
- Operational history: years in business, client complaint record, dispute resolution track record
- Concentration: avoid single‑provider concentration if your position represents >5%–10% of net worth
Practical rule: if your holding is a meaningful percentage of your net worth, split custody after modeling transfer costs and minimum fees.
Technology and Tokenization — What Changed and What Didn’t
Tokenized gold and digital interfaces grew further through mid‑2026. Here’s what to verify now:
- Does the token represent legal title to specific bars, or a claim on a pooled inventory? The latter is common.
- Do on‑chain attestations reconcile to a bar list? Public attestations reduce opacity but are not a substitute for contractual title.
- Has an independent third party performed periodic reconciliations and published reports? Prefer platforms that provide signed attestations reconciled to serial numbers.
Bottom line: improved tech reduces operational friction and improves audit trails, but cryptographic records do not change legal title or insolvency priorities unless the contract gives token‑holders direct rights to specific bars.
Common Mistakes (and How to Avoid Them)
- Equating “allocated” with “segregated”: allocation can still be commingled—decide if segregation is worth the cost.
- Not obtaining a bar list: without serials you can’t verify specific‑bar ownership.
- Ignoring minimums: percentage fees with dollar minimums can make small allocations uneconomic.
- Assuming insurance covers provider fraud: most policies exclude fraud/misrepresentation unless specified.
- Underestimating exit friction: buy premiums are visible; sell spreads and admin charges often only surface at liquidation.
Pro Tips: How to Get Better Terms and Stronger Verification
- Get explicit contract language on title and insolvency treatment before funding. If the provider can’t produce it in writing, walk away.
- Model total cost in basis points: buy premium + sell spread + (annual fees × years) + exit fees. Compare products for your intended horizon.
- Prefer formula‑based pricing (spot reference + stated spread) over “at our discretion” pricing.
- Match bar size to exit plan: smaller bars increase premiums and delivery costs. If you want flexibility, favor 1 kg or 100 g over 1 oz where feasible.
- Keep complete documentation: agreement, bar lists, audit attestations, transfer confirmations—and back them up offline.
FAQ
Does “allocated” guarantee I can take delivery of my exact bars?
No. Many programs permit delivery, but contracts commonly allow substitution, require minimum sizes, or impose fabrication and handling fees. Confirm delivery terms, fees, and lead times in writing before you buy.
Are tokenized gold products the same as allocated physical gold?
Not necessarily. Some tokenized products are backed by specifically allocated bars and publish attestations; others represent claims on pooled metal. Verify whether the token grants legal title to specified bars and request independent attestation reconciling token balances to a dated bar list.
What is a reasonable annual custody fee in mid‑2026?
Retail allocated custody generally sits in the ~0.10%–0.60%/year range, depending on jurisdiction, insurance structure, and service level. High‑volume institutional programs can be lower; retail accounts often face dollar minimums—check both percentage and floor.
Is segregation required to protect my ownership?
No. Properly recorded allocated‑but‑commingled holdings can be acceptable if independent reconciliations and clear title language exist. Segregation reduces operational ambiguity but usually costs more—decide based on your use case and position size.
What records should I keep to prove ownership?
Keep your signed account agreement, periodic statements showing bar serials and weights, the bar list export, independent audit or vault attestation, and any transfer confirmations. Well‑organized documentation materially reduces friction if disputes or transfers arise.
Disclosure: This guide is educational and does not constitute individualized investment, tax or legal advice. Terms, taxes and regulations vary by jurisdiction—verify with your provider and consult a professional for your situation.