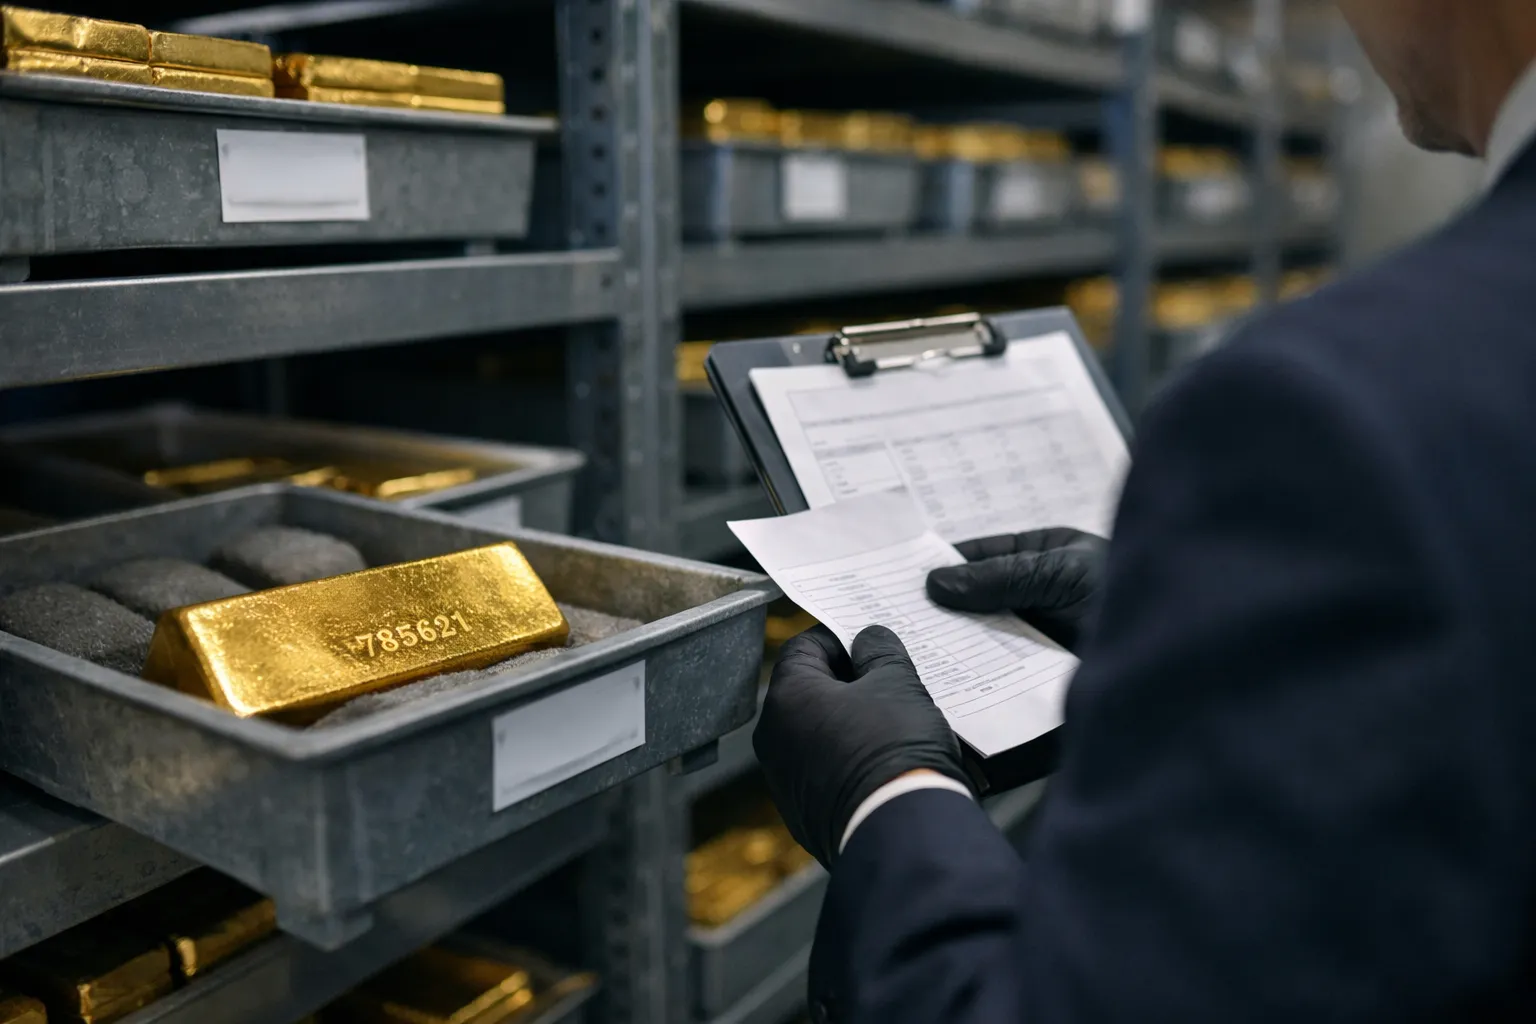
Retail and high‑net‑worth investors who hold allocated physical gold increasingly ask the same question in 2026: how can I earn yield from my holdings without giving up title or taking undue counterparty risk? This guide walks you through practical, actionable options—secured gold loans, vault‑custodian lending programs, and carefully selected third‑party yield platforms—and explains the operational, legal and tax steps to turn allocated bullion into income while preserving safety.
Who this guide is for
- Owners of allocated physical gold (bars or coins) seeking income without immediate sale
- Investors considering lender or platform offers to monetize allocated holdings
- Advisors conducting due diligence on gold‑backed lending and yield products
Overview: three practical yield routes for allocated gold
Three routes dominate the market in 2026. Each balances yield against custody, legal title and counterparty risk:
- Secured gold‑backed loans (you as pledgor) — Use allocated gold as collateral for a loan in cash or stablecoin; you retain title but lender takes a lien or pledge.
- Custodian‑run lending programs — Some global custodians run programs that allow vaulted allocated gold to be lent to institutional borrowers with returns passed to participants.
- Vetted third‑party yield platforms — Tokenized or account‑based platforms offer yields for deposited allocated gold via market mechanisms; these can deliver higher nominal yield but often carry more operational risk.
Key tradeoffs
- Price of yield vs. counterparty exposure: higher yields typically require accepting more counterparty or rehypothecation risk.
- Title vs. possession: secured loans generally preserve investor title; some platform models transfer title or permit rehypothecation.
- Liquidity: loans/locks often restrict immediate physical redemption; programs vary on recall mechanics.
Step‑by‑step: how to convert allocated gold into yield (practical checklist)
Step 1 — Inventory and eligibility check
- List each holding: bar serial numbers, assay certificates, weight, fineness, custodian and vault location.
- Confirm allocation status in writing (allocated vs unallocated). Only allocated holdings generally qualify for the models described here.
- Check custodian policies. Some custodians already permit participation in lending programs; others prohibit third‑party lending against allocated holdings.
Step 2 — Define objectives and constraints
- Target yield range (net, after fees): conservative (0.5–2%), moderate (2–4%), aggressive (4%+).
- Maximum acceptable counterparty exposure and permitted rehypothecation.
- Liquidity needs: immediate physical redemption vs. notice periods.
- Tax and reporting constraints in your jurisdiction.
Step 3 — Select the route and shortlist providers
Match your constraints to available routes:
- If preservation of title and minimal counterparty risk are paramount: prioritize secured loans from regulated banks or specialist bullion lenders who take a lien but do not take title.
- If you accept some operational complexity but want institutional credit worthiness: consider custodian‑run vault lending pools operated by large vault custodians (subject to their program disclosure).
- If you prioritize yield and can accept extra counterparty and technological risk: include audited tokenized‑gold yield platforms with transparent reserve reporting.
Shortlist providers by asking for:
- Proof of regulatory status and licensing
- Sample contractual terms (loan agreement, pledge notice, custody agreement)
- Recent independent audit reports and proof of insurance
- Operational flow diagrams showing movement, recall and settlement
Step 4 — Due diligence questions to ask every provider
- Do you require transfer of legal title, or only a lien/pledge? Can you document this in the contract?
- Is rehypothecation permitted? If yes, under what limits and disclosures?
- Where is the metal held? Are vaults segregated for this program?
- What insurance covers the bullion while on loan or in program custody? Who is the insurer and what are policy limits and exclusions?
- What margin/haircut is applied and how is it recalculated? What is the margin call process?
- What are the termination and recall mechanics for the investor seeking physical delivery?
- How is interest/yield calculated and paid (cash, bullion, or tokenized credit)? What fees exist?
- What is the bankruptcy and insolvency treatment of pledged metal in the provider’s jurisdiction?
Step 5 — Read and negotiate contract details
Key clauses you should focus on and, where possible, negotiate:
- Lien vs title: Prefer a pledge/lien that specifically states you retain ownership and the lender’s remedy is limited to sale under contractual procedures.
- Rehypothecation clause: If present, cap the percentage of your allocation that can be rehypothecated and require sub‑segregation accounting.
- Insurance and loss allocation: Define who bears uninsured loss; require named insured and global policy references.
- Valuation methodology and haircuts: Specify which spot price source, timing and currency are used and dispute resolution.
- Events of default and cure periods: Ensure reasonable cure windows and limits on acceleration.
- Audit and reporting: Right to periodic independent audit reports and proof of physical presence.
Sample economic example (illustrative)
Assume you hold 100 ounces of allocated gold and negotiate a secured loan at a 70% loan‑to‑value (LTV) with a 3% annual interest rate on cash drawn.
- If gold market value = P per ounce, loan amount = 100 × P × 70% = 70P.
- Annual interest cost = 70P × 3% = 2.1P.
- If you instead participate in a custodian lending program promising a 1.5% net yield on the underlying metal, your annual nominal yield = 100 × P × 1.5% = 1.5P.
Tradeoff: loan delivers immediate liquidity (but interest cost), custodian program delivers yield on the underlying asset but can reduce immediate physical claimability while the metal is committed to the lending pool. The highest reported platform yields may be higher, but require accepting more complex operational risk.
Tax, regulatory and insolvency considerations
Tax treatment varies by jurisdiction—income may be classified as interest, capital gains, or other income streams depending on structure. Key points:
- Secured loan interest is usually deductible in the same way as other interest for investors who can benefit from that treatment—confirm with tax counsel.
- If title transfers (e.g., certain tokenized models or sale/re-purchase structures), you may trigger a taxable sale event with capital gains consequences.
- Bankruptcy laws matter: in some jurisdictions a pledge is treated as secured property outside bankruptcy estate; in others, operational practices may not perfectly insulate pledged metal. Always confirm with legal counsel familiar with local insolvency law.
Operational controls and monitoring
Once live in a program, implement these ongoing controls:
- Monthly custodial confirmations and audit reports
- Monitoring of provider credit and insurance changes
- Price‑sensitivity checks and scenario stress tests for margin calls
- Periodic legal review of contract renewals and amendments
Exit strategy: how to get your metal back
Plan exit mechanics before committing. Common pathways:
- Notice periods: some programs require 7–30 days notice for physical delivery.
- Buyback or closeout: if your metal is rehypothecated, you may need the provider to unwind positions—confirm maximum unwind times and fees.
- Forced sale mechanics: if you default, understand the provider’s sale process and notification steps.
Risk checklist — what can go wrong
- Counterparty default where pledged metal becomes subject to claims
- Operational failures: custody errors, audit gaps or insurance shortfalls
- Market moves triggering margin calls and potential forced liquidation
- Legal/ tax treatment differences that create unexpected liabilities
- Technology or governance failures at tokenized platforms
Practical tips and best practices
- Limit exposure: initially allocate a modest share (e.g., 10–25%) of total allocated holdings to yield programs while you validate provider performance.
- Prefer large, regulated custodians and counterparties with transparent audits.
- Insist on segregation and serial‑level reconciliation for any program reporting aggregated holdings.
- Document everything: scans of assay certificates, signed custodial statements and contract exhibits should be stored offsite and with counsel.
- Engage specialist counsel and tax advisers before signing complex or cross‑border agreements.
Where yields stand in mid‑2026 (context)
As of mid‑2026, the market for monetizing allocated gold remains nuanced. Institutional balance‑sheet pressure has tightened some traditional bank liquidity channels, making secured personal loans a widely used pathway but often at tighter LTVs and stricter haircuts. Emerging platforms continue to offer attractive headline yields but require rigorous proof of reserves and independent audits. Always reconcile advertised yields with the full fee and custody cost picture.
Quick decision checklist before committing
- Do you retain title or does title transfer? (Prefer pledge/lien.)
- Can you obtain independent audit reports and insurance certificates?
- Are margin/haircut and recall terms acceptable for your liquidity needs?
- Have you modeled tax consequences for sale vs. loan structures?
- Have you limited initial exposure while validating provider performance?
Conclusion: balance yield with safety
Allocated physical gold can be a source of yield without a sale, but doing it safely requires careful matching of objectives to structure, disciplined due diligence and conservative legal protections. For many investors the optimal approach in 2026 will blend a small, well‑documented participation in custodian programs with selective secured loans from regulated counterparties, while avoiding opaque tokenized promises unless independent audits and legal ownership protections are rock solid. Consult counsel, start small, and require clear contractual language that preserves your ownership and access to the metal.
If you want, our next guide will provide a sample redlined pledge agreement and a template due‑diligence questionnaire you can give to providers. Contact the Gold Investment News editorial desk for that addendum.