London — 18 August 2026: Three months after the Prudential Regulation Authority (PRA) published its final policy on custody and vaulting of physical precious metals on 12 May 2026, the market has moved from planning to price‑setting. Gold Investment News’ follow‑up survey of 18 custodians conducted 1–10 August 2026, LBMA guidance published in July, and public filings from regulated funds show a clear pattern: custodians are implementing fee increases, some clients are shifting or diversifying custody jurisdictions, and insurers and reinsurers have re‑priced the tail risk that the PRA targeted. This update explains what has happened, why it matters for your costs and liquidity, and what practical steps investors should take now.
Why this update matters now
The PRA’s May 12 policy brought bank‑style prudential requirements — clearer legal title, segregation, capital/insurance buffers and regular attestations — to a market long governed by market practice. Those protections reduce counterparty risk but have explicit costs. Since May, custodians and insurers have started to translate regulatory obligations into client fees and operational changes. For anyone holding London custody or relying on London settlement windows for financing chains, the next 6–12 months will determine whether the PRA’s rules materially change total cost of ownership or intraday liquidity.
What changed between May and August 2026
- Custodian fee moves: In our August survey, 12 of 18 custodians said they had notified clients of fee increases or planned increases for Q3–Q4 2026. Institutional clients were quoted incremental rises generally in the 5–25 basis‑point range (0.05%–0.25%) on assets under custody; smaller retail allocated accounts showed much larger proportional increases once fixed admin pass‑throughs were included, with custodians estimating effective rate rises in some bespoke cases of 50–200 basis points.
- LBMA guidance published: The London Bullion Market Association issued updated vaulting guidance and an allocation‑certificate template on 30 July 2026 to help align industry paperwork with the PRA’s prescribed legal forms. The LBMA guidance emphasises quarterly third‑party attestations and standardised client disclosure wording — both items the PRA mandated.
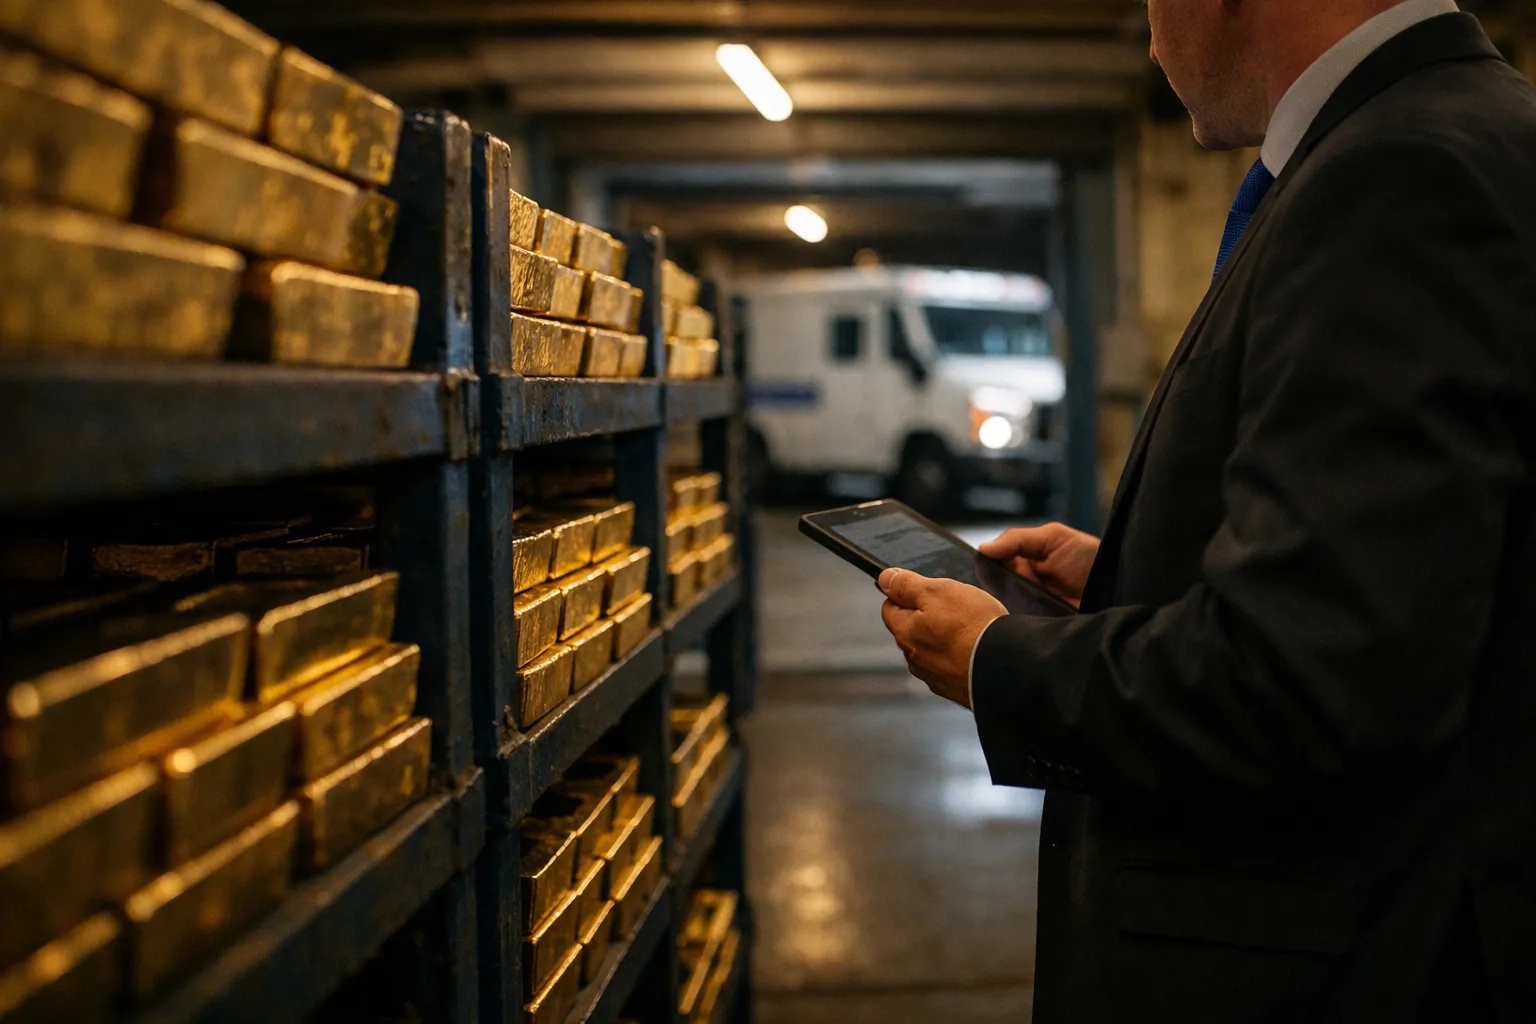
- Vault flows and inventories: Market participants estimate London vault inventories remain above £100 billion, but custodians reported modest net outflows in June–July 2026 as some clients opened or re‑activated balances in Amsterdam, Zurich and Dublin. Multiple vault operators told Gold Investment News that cross‑jurisdictional transfers are happening more as a diversification strategy than a wholesale relocation — moving a portion of holdings as a secondary liquidity line rather than a rush exit.
- Insurance and reinsurance repricing: Insurers have tightened wording and pushed premiums higher for policies explicitly covering insolvency‑related client loss scenarios. Several custodians reported insurer requests for higher retentions or co‑insurance and limited capacity for very small retail accounts, which further raises effective costs for bespoke holders.
- Fund and ETF operational changes: Regulatory filings in July and August 2026 show at least a half‑dozen UK‑domiciled funds and London‑listed ETFs updating prospectuses or custodian appointments to consolidate custody with regulated entities in Dublin or Luxembourg, or to clarify allocation and delivery processes in line with PRA expectations.
Details that matter to investor costs and liquidity
Two mechanics drive most of the investor impact: (1) increased per‑account operating costs and insurer pass‑throughs; and (2) legal/operational choices that increase the value of allocated metal relative to pooled/unallocated holdings. For a £1 million allocated holding, a 20 basis‑point incremental custody charge equals £2,000 a year — small for long‑term allocators but meaningful for smaller accounts or thin‑margin strategies that use gold as collateral. For retail investors with accounts under £100,000, fixed admin charges spread over small balances can move effective rates into double digits percentage‑wise.
Who is seeing the biggest effect
- Small retail allocated accounts and bespoke family‑office arrangements face the largest proportional increases because insurers and custodians apply minimum administrative costs.
- Non‑bank vault operators are managing capital and insurance financing costs, and some are reviewing their UK footprint; a subset has accelerated expansion plans in Amsterdam and Zurich.
- Large institutions and index funds see smaller basis‑point increases in percentage terms, but operational changes (attestations, monthly reconciliations) create workflow and reporting costs that must be absorbed or negotiated.
Stakeholder reactions (August 2026)
“The PRA’s approach targets a real risk in the chain between collateral and financing,” a PRA spokesperson told Gold Investment News on 22 July 2026. “Our implementation timetable is phased to allow firms and markets to adapt — supervisors are engaging bilaterally on firm plans.”
A trade body representing logistics and vault operators welcomed the LBMA template but said in a 5 August 2026 statement that insurers’ initial pricing actions had been “sharper than expected” and asked for continued supervisory dialogue on proportionality for small retail providers.
Practical, ROI‑focused checklist — what to do now
- Confirm allocation and legal wording now: Ask your custodian for the LBMA‑aligned allocation certificate and written confirmation of whether your holdings are allocated or unallocated under PRA terms.
- Request the latest attestations: Demand the custodian’s latest independent inventory attestation and the cadence of future reports. Prioritise providers that publish quarterly third‑party attestations for allocated holdings.
- Re‑model total cost of ownership (TCO): Update your custody model to include new line items: additional basis points, insurance pass‑throughs, one‑off transfer costs, and administrative minimums. For institutional portfolios, run sensitivity analyses at +10, +20 and +30 bps; for retail or small bespoke accounts, calculate per‑account fixed costs as dollar/ounce and percentage impacts.
- Consider a secondary jurisdiction, not a reflexive move: Maintaining a smaller secondary pool in Amsterdam, Zurich or Dublin can preserve settlement chains while avoiding a full transfer. Moving metal has direct costs, tax/legal implications and potential settlement delays — treat it as strategic diversification.
- Negotiate transitional mechanics: For sizeable allocations, seek multi‑year fee caps or phased fee pass‑through tied to PRA implementation milestones and insurer contract renewals.
Impact on market liquidity and pricing
Allocated metal continues to trade at a premium to pooled/unallocated positions. Dealers say pricing already incorporates custody certainty for small allocated lots and cross‑jurisdictional delivery friction. Expect intraday liquidity in London to remain functional, but operators and market‑makers will continue to price in custody and delivery certainty for smaller transactions or those dependent on cross‑border chains.
What to watch next (timelines and signals)
- Custodian implementation plans: Watch for firm‑level implementation filings and client communications in Q3–Q4 2026. These will show whether custodians take the full cost or pass it through.
- Insurer/reinsurer renewals: Major renewals in September–November 2026 will be telling for premiums and policy wording; expect another wave of client notices thereafter.
- LBMA and market templates uptake: Monitor how many custodians adopt the LBMA allocation certificate template — wider adoption will reduce legal friction but not necessarily per‑account costs.
FAQ — Common investor questions (updated August 2026)
Do I need to move my gold out of UK vaults immediately?
No. Immediate moves are rarely optimal. Assess your custody agreement, allocation status and the full cost of moving (transport, insurance margin, tax/legal). For most investors, opening a secondary custody line or renegotiating fees is a better near‑term option than a rushed transfer.
Are insurers still limiting coverage for small retail accounts?
Yes — insurers and reinsurers have tightened capacity and increased premiums for small bespoke accounts. Expect higher effective costs where providers require minimum administration fees or higher retentions; negotiate or pool with other investors where possible.
Will allocated gold be safer under the PRA rules?
Yes — allocated holdings will generally have clearer legal protection, stronger segregation and reduced re‑hypothecation risk. That protection comes at a price: balance your counterparty‑risk tolerance against the ongoing TCO.
What is the single most useful question to ask my custodian right now?
“Provide your latest independent inventory attestation, the specific LBMA/PRA allocation wording you will use for my holdings, and a client‑level estimate of the total incremental annual cost (bps and fixed fees) attributable to PRA compliance.” If the custodian can’t answer all three clearly, treat that as a negotiation lever.
Consider your situation, time horizon and the scale of your holdings before making changes. The PRA’s rules materially reduce certain counterparty risks, but they do not remove transport, settlement or geopolitical risk — and those protections carry measurable costs. For many investors the smartest step in August 2026 is a deliberate re‑pricing and negotiation of custody terms, not a reflexive relocation.