Overview
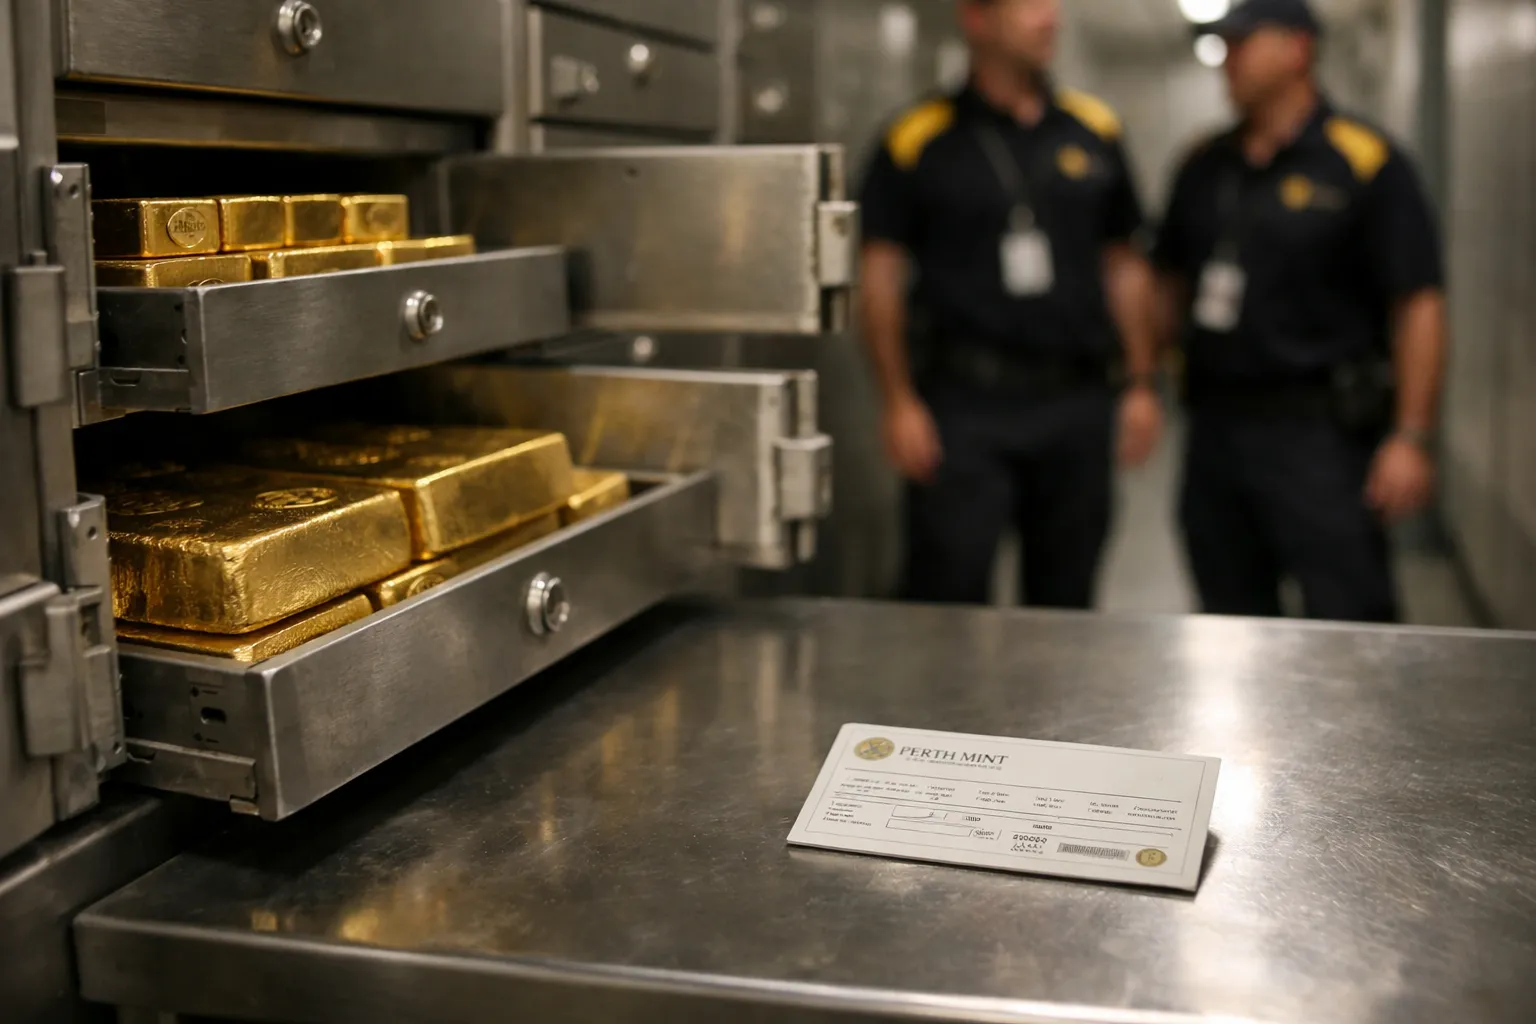
The Perth Mint Certificate Program (PMCP) is an allocated bullion custody service that issues certificates tied to serial‑numbered bars or coins held in the Perth Mint’s vaults in Western Australia. This August 2026 update evaluates PMCP on the metrics gold investors care about most: custody security, transparency, onboarding and compliance, all‑in cost, liquidity and redemption mechanics — and gives practical, current guidance to compare PMCP to ETFs and private allocated vaults.
Background
The Perth Mint is a statutory authority owned by the Government of Western Australia. PMCP certificates identify specific, serial‑numbered metal that the Mint holds on an investor’s behalf; in legal terms this is allocated title rather than an unallocated or pooled claim. That distinction continues to make PMCP attractive to investors who prioritize provenance, traceability and an auditable title chain.
Features analysis
Allocation and documentation
PMCP still issues certificates that name serial numbers and weights for the allocated metal. For estate planning and provenance-sensitive buyers (for example, numismatists or institutions requiring audited title), this remains the key advantage over pooled structures like most physical ETFs. If you need paper or certified PDF documentation for trust or legal purposes, confirm the exact wording and transfer form you will receive before purchase.
Custody, audits and insurance
The Mint operates high‑security vaults and publishes audit and custody terms. As of August 2026, investors should specifically check three items before committing funds: (1) the identity of the independent auditor and the frequency of attestation reports; (2) the Mint’s current insurance cover wording and per‑client limits; and (3) the custody provider chain (whether any third‑party sub‑custodians are used). Global insurance markets have hardened since 2022–24, raising replacement and transit cover costs — that pressure is often passed to clients via higher custody or handling fees.
Onboarding and compliance
Anti‑money‑laundering and beneficial‑ownership transparency remain a practical friction point. Australian regulator AUSTRAC’s guidance and international FATF expectations have pushed bullion custodians to require robust KYC and source‑of‑funds evidence. For non‑residents, expect identity checks, certified documents and occasionally notarised declarations; onboarding windows of 5–15 business days are common depending on completeness of documents and intermediary broker requirements.
Digital records and transferability
Across the bullion industry, tokenization pilots and ledgered transfer services advanced through 2024–26. However, sovereign mints and long‑standing allocated programs generally adopt change cautiously. As of August 2026, PMCP continues to rely primarily on certificate documentation and established broker networks for transfers. If you require near‑instant, blockchain‑style transferability, verify whether your trading counterparty or broker can accept PMCP certificates into any ledgered marketplace — don’t assume automatic digital interoperability.
Redemption mechanics
Redemption remains possible for physical delivery or sale back to the Mint/approved brokers, subject to minimums, verification and lead times. Practical realities have not changed: expect several business days for sale settlements and days‑to‑weeks for cross‑border physical delivery because of insurance, customs and handling. If you plan to take delivery, request the Mint’s current minimums by metal type and the full list of shipping and export documentation required to your jurisdiction.
Pros and cons — what’s new in 2026
Pros
- Allocated title and provenance: Serial numbers and certificate wording remain useful for estate planning and collectors.
- Sovereign custodian credibility: Government ownership still supports continuity of operations and public oversight.
- Audit trail: Independent attestation reports continue to be a differentiator vs pooled products.
Cons
- Cost pressure from insurance and compliance: Custody and handling fees have been under upward pressure industry‑wide; smaller accounts feel this most.
- Operational latency: PMCP is not designed for intraday trading — ETFs remain the better option for liquidity.
- Limited digital transfer convenience: Tokenization pilots exist across the market, but PMCP’s mainstream workflow still relies on traditional certificate and broker transfer mechanics.
Pricing and value — updated practical method
PMCP’s cost profile still breaks into purchase premium, annual custody/storage fees and redemption/handling charges. Because fees change and currency conversion affects cross‑border investors, use an illustrative example as a practical comparison tool. These numbers are illustrative — obtain written quotes for your specific bar/coin mix and delivery options.
Illustrative example (A$100,000 starting allocation at spot parity):
- Illustrative purchase premium: 1.2%–1.8% (retail premium depends on product mix; smaller coins generally carry higher premiums).
- Illustrative annual custody fee: 0.20%–0.30% (pressure from insurance and compliance has nudged some programs upward since 2024).
- Illustrative redemption/handling: A$250–A$500 flat plus shipping/insurance for physical delivery (varies with destination).
Under these assumptions a first‑year all‑in cost for a retail buyer could reasonably land in the 1.4%–2.1% band (purchase premium + one year custody), plus exit costs amortized over your holding period. For context, major physically‑backed ETFs still offer materially different economics and liquidity: SPDR Gold Shares (GLD) has historically carried an expense ratio around 0.40% and iShares Physical Gold (IAU) around 0.25% — but ETFs represent pooled holdings rather than serial‑numbered allocated metal.
Key point: allocated custody buys title and provenance at a price. Always request a written estimate that itemises premiums, custody, audit fees, insurance limits and redemption charges, then annualise those costs for your planned holding horizon.
Liquidity and market context — August 2026
If your priority is intraday liquidity or trading tight spreads, ETFs remain superior. For larger blocks and buy‑and‑hold allocations, PMCP provides operational liquidity through approved broker channels, but settlement is measured in days and sometimes requires enhanced verification for larger transfers. Recent market conditions (post‑2024 insurance repricing and tighter AML checks) mean that settlement timelines for physical delivery can be longer than historical norms — plan accordingly.
Who it’s for
- Buy‑and‑hold investors who value allocated title, auditability and sovereign custody.
- Collectors and institutions requiring serial‑numbered provenance for legal or fiduciary reasons.
- High‑net‑worth clients for whom custody charges are a small percentage of portfolio value.
It is less suitable for intraday traders, small retail buyers for whom premiums dominate returns, or investors who need instant, ledgered transferability unless you confirm a compatible third‑party platform.
Alternatives
- Physical ETFs/ETCs: GLD, IAU — lower liquidity friction and intraday trading but pooled exposure without serial allocation.
- Private allocated vaults: London and Swiss providers (Brinks, Loomis, Malca‑Amit) — competitive storage rates for larger accounts; compare audit cadence and insurance scope.
- Home or safe‑deposit storage: Maximum direct control; owner bears security, insurance and logistics responsibilities.
Practical checklist before you commit
- Request the Mint’s current written fee schedule and a sample certificate.
- Obtain the independent auditor’s latest attestation and insurance certificate (check per‑client limits).
- Confirm onboarding timeline and required KYC documents for your residency status.
- Ask whether your broker or trading platform accepts PMCP certificates for transfer or marketplace listing.
- Model first‑year and annualized costs against ETF expense ratios and private vault quotes for the same allocation size.
Verdict
As of August 2026, the Perth Mint Certificate Program remains a credible option for investors who prioritise allocated title, provenance and the backing of a sovereign mint. The program’s strengths are unchanged: specific‑bar ownership, audit trails and institutional custody. What has changed is the operating environment — higher insurance costs, sustained regulatory tightening and uneven adoption of ledgered transfer systems have raised the premium for allocated custody. If provenance and legal title are central to your goals, PMCP is worth the likely extra cost; if you prioritise liquidity or lowest ongoing fees, evaluate ETFs or large private vaults and run a side‑by‑side cost model for your specific holding size.
Disclaimer: This article is informational and not financial advice. Fee figures are illustrative. Confirm current rates and legal terms with the Perth Mint and seek personalised advice from a qualified financial or tax professional.
FAQ
How quickly can I redeem PMCP holdings for cash or physical delivery?
Redemption for sale typically settles in several business days; physical delivery can take days to weeks because of handling, insurance and customs. Larger or cross‑border orders may trigger enhanced verification and take longer.
Does PMCP insure my metal while it’s stored?
The Perth Mint maintains insurance for metal in its custody. Insurance wording, per‑client limits and covered perils can change — request the current insurance certificate and read the exclusions before you commit.
Can I move PMCP certificates into a digital ledger or tokenized marketplace?
Adoption of tokenized ownership is growing across the industry, but sovereign mint programs typically maintain traditional certificate workflows. If ledgered transferability is essential, confirm in writing whether your broker or platform accepts PMCP certificates into its marketplace.
How do taxes and customs affect cross‑border redemptions?
Cross‑border delivery can involve export declarations, import duties in some jurisdictions and different tax treatments on sale or delivery. Tax consequences depend on your residence and local law; consult a tax adviser before arranging physical delivery.
What’s the simplest way to compare all‑in costs versus an ETF?
Calculate first‑year all‑in cost as: purchase premium + annual custody/storage fee + amortised expected redemption/handling. Compare that to an ETF’s expense ratio plus brokerage costs and bid/ask spread. Run the numbers for your planned holding horizon (3, 5, 10 years) to see which option is cheaper net of the services you value.