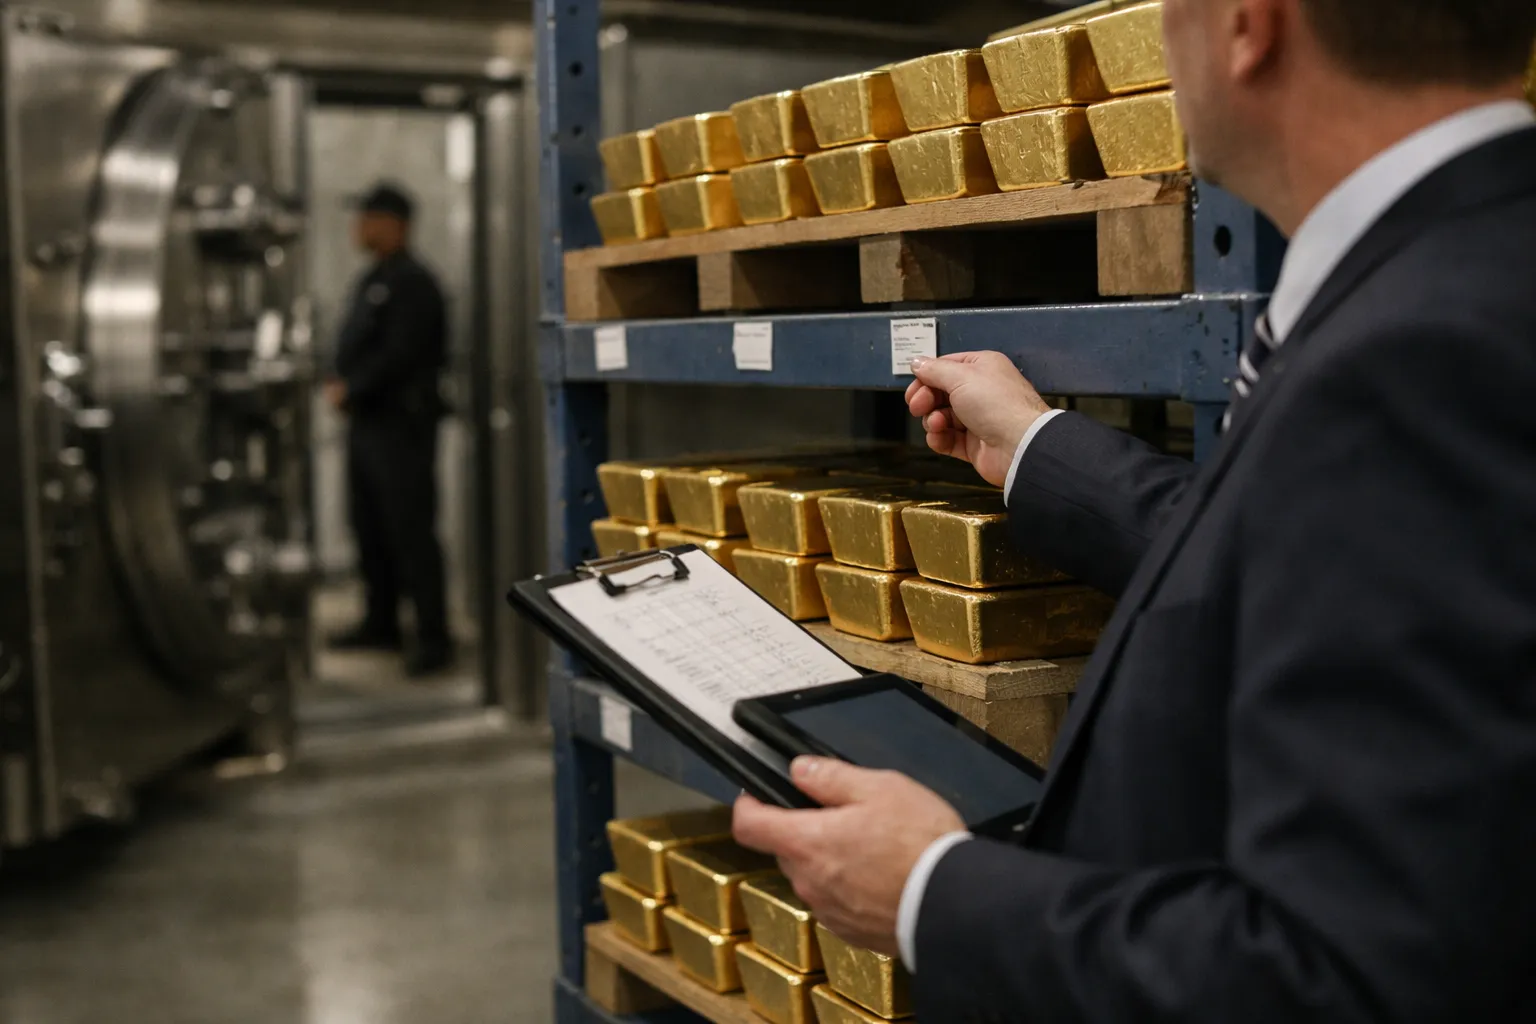
From late 2023 through mid‑2026 the gold market repeatedly surprised observers who expected central‑bank buying and investor demand to be the dominant drivers of price direction. Instead, on multiple occasions the tighter margin on physical delivery and episodic premium spikes reflected an often overlooked dynamic: the interaction between structurally constrained mined supply and the elastic — but lagged — response of household and industrial scrap. For gold investors this supply‑side story changes how one reads price signals, evaluates bullion liquidity, and chooses exposure.
What happened: supply tightened for reasons beyond headline demand
Two supply channels matter for bullion markets: primary (mine) production and secondary (recycling/scrap). In 2024–mid‑2026 both channels produced surprises, not because of a single shock but due to the confluence of persistent underperformance at mines and a slower, price‑sensitive pick‑up in scrap.
- Mine production underperformed expectations. Years of underinvestment in greenfield exploration and shorter project pipelines left the industry vulnerable to incremental disruptions. Operators reported lower grades at mature orebodies, permitting and ESG‑related delays in new projects, and operational headwinds — from energy costs to water constraints — that reduced throughput in several producing regions. These factors limited the upside in primary supply even when prices were supportive.
- Recycling is elastic but delayed. Unlike many industrial commodities, a large portion of gold supply comes from melting down existing metal — jewellery, electronics, and coin bars. Scrap supply responds to price, but household, retail and commercial channels introduce frictions: cultural attachment to jewellery, costs of assay and sale, and local cash needs. When prices rally, scrap increases, but the flow often comes after a lag and is sensitive to local liquidity conditions and refining bottlenecks.
The result: when demand stepped up (investment flows, festival and wedding seasons, or intermittent central‑bank purchases), the immediate available physical metal for settlement was thinner than models that assume smooth, predictable supply suggested. That mismatch showed up as higher spot premiums in regional markets, tighter allocations at refineries, longer lead times for bars, and occasional backwardation in the nearest physical settlement windows.
Mechanics that amplified tightness
Understanding why these supply constraints mattered to price requires looking at how market microstructure transmits physical tightness into observable metrics.
- Refiner and logistics capacity. Even if households decide to sell jewellery, refiners and vaults need available capacity. Periods in 2024–26 saw refiners running near‑capacity during local demand spikes. Lead times for assay and delivery lengthened, creating temporary shortages for allocators and dealers.
- Regional frictions and routing choices. Not all metal is fungible on a same‑day basis. Moving doré from a mine in South America to a refinery in Switzerland or a vault in Dubai entails shipping, customs, and insurance. Those frictions mean local tightness can persist even if global balances look adequate.
- Inventory management by intermediaries. Bullion banks and dealers kept inventory lean after earlier cycles where carrying costs punished oversized stockpiles. That lean posture reduced available buffer during spikes.
How this showed up in market data and pricing
Investors observed the supply tightness through several concrete market signals:
- Widening spot‑premium dispersion. Premiums in regional physical markets — London, Zurich, Dubai, Singapore, and key Asian centers — diverged episodically as local scrap and refiner availability varied.
- Tighter prompt settlement windows. Dealers increased lead times and allocations for allocated bars; some investors faced backorder queues for popular bar sizes during peak demand weeks.
- Occasional basis/backwardation behavior. Short‑dated physical forwards and the nearest futures basis tightened relative to longer‑dated contracts during acute tightness, reflecting immediate settlement pressure.
- Refinery throughput and prime‑grade ore signals. Public reporting from major refiners and producer guidance repeatedly cited longer processing times and grade declines — early warning signals for constrained primary supply.
Why central‑bank purchases were only part of the story
Central‑bank buying continued to be a meaningful source of demand in 2024–26, but it often received disproportionate attention relative to the structural supply picture. Central banks typically operate through planned, announced purchase programs and established channels; those flows are relatively predictable once disclosed. By contrast, supply side constraints — unexpected mine underperformance, refinery bottlenecks, and regional scrap lag — produce more abrupt and less visible shortages that can move short‑term premiums and liquidity more sharply.
Investor implications — what to watch
For bullion investors the supply‑side emphasis suggests different monitoring and positioning than a pure macro‑oriented trade. Key indicators to track:
- Mine guidance and capex trends. Quarterly production guidance and changes in sustaining capital from major producers are leading indicators of primary supply stress.
- Refiner lead times and bar availability. Ask your dealer for current delivery windows for common bar sizes and note changes in offered premiums and minimum order quantities.
- Regional premium spreads. Watch spot premium differentials across London, Zurich, Dubai and Singapore. Persistent spreads indicate routing or logistical constraints.
- Scrap proxies. Monitor secondary indicators such as local jewellery merchant inventories, refinery throughput reports, and scrap gold imports/exports where data are available.
- Physical futures basis. Near‑date backwardation or narrowing negative basis can signal immediate settlement pressure.
Practical strategies for investors
No single strategy fits all investors, but the supply‑tightness environment favors certain approaches:
- Prioritise allocated holdings where counterparty concerns matter. During physical tightness, access to allocated bars can be constrained. Investors who need immediate physical delivery should keep some allocated metal in well‑connected vaulting centers to avoid long backorder queues.
- Size exposures to miner equities selectively. Low‑cost producers with strong balance sheets benefit if physical tightness supports higher price realizations. Focus on companies with predictable production and transparent cost structures.
- Consider liquidity and timing for ETF redemptions. Physically backed ETF arbitrage mechanisms can strain during regional tightness. If planning large redemptions, hedge for potential premium and timing costs.
- Use options to express a view on volatility rather than directional bets alone. Supply‑driven tightness often manifests as volatility spikes. Vertical spreads or put spreads can capture convexity without full directional exposure.
- Watch bar size and location as cost levers. Premiums differ by bar size and vault location; smaller bars and certain vault locations command higher premia during tightness. Trading across these dimensions can lower acquisition cost.
Outlook through the rest of 2026
As of mid‑2026 the market sits in a state where supply elasticity exists, but the timing of that elasticity is the critical unknown. If recycling accelerates materially and refiner capacity is expanded, some of the tightness will dissipate; conversely, if mine underperformance deepens or logistics bottlenecks recur, premiums and short‑term volatility may reappear even if macro drivers remain stable.
For committed gold investors the practical takeaway is to treat physical access and delivery risk as part of portfolio construction — not just price risk. In markets where tightness is more likely to be supply‑driven and episodic, liquidity planning, diversified custodial relationships, and selective operational hedges will typically outperform purely macro timing strategies.
Ultimately, understanding gold requires reading both demand headlines and the quieter mechanics of supply. In 2024–mid‑2026 the latter proved at least as consequential for prices and liquidity. Investors who track refiners, mine health, and scrap flows gain an informational edge in anticipating when a price move will be temporary premium dislocations — or the start of a more durable repricing.