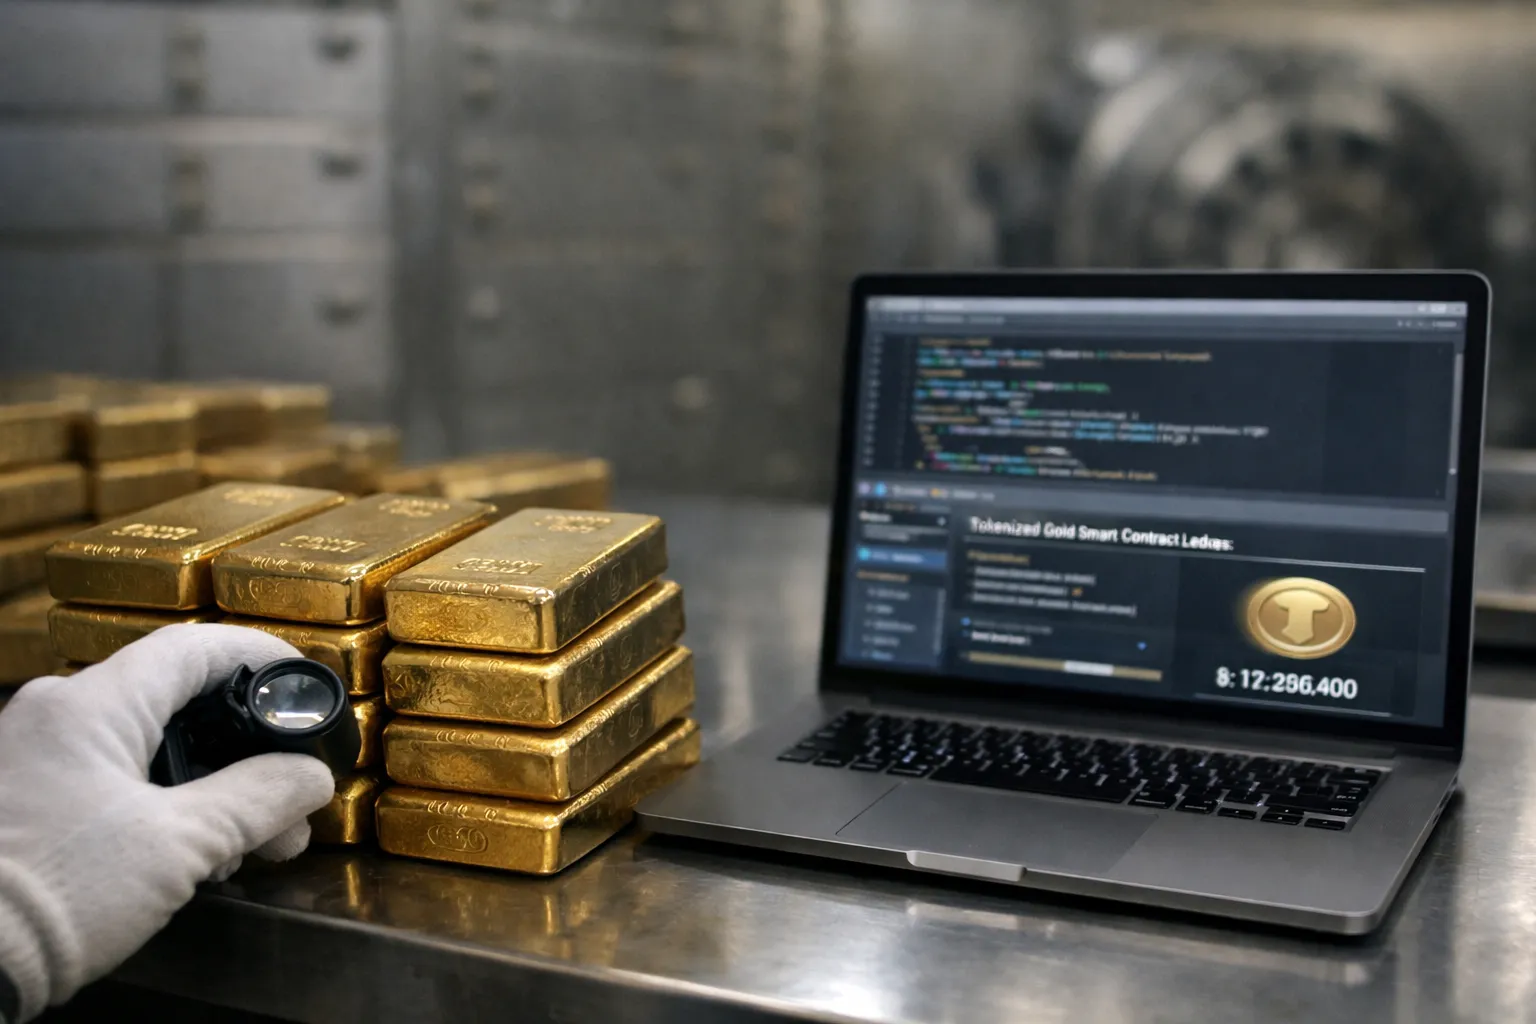
Tokenized gold — blockchain-based tokens that claim to represent allocated physical metal — attracted renewed interest through 2024–2026 as exchanges, custodians and asset managers launched or expanded offerings. For gold investors weighing tokenized products against traditional allocated bullion (bars, coins held in allocates vaults) the differences are not merely semantic. Structure, transparency, liquidity and legal rights vary, and those differences matter for portfolio risk, cost and the ease of converting holdings back into physical metal.
What 'tokenized' actually means
At its simplest, a tokenized gold product issues digital tokens on a blockchain where each token is claimed to be redeemable for a specified quantity of physical gold (commonly one fine troy ounce or one gram). Established examples in the market include long-standing programs such as Pax Gold (PAXG) and Tether Gold (XAUt), which represent units of allocated bullion held by custodians. Newer entrants since 2024 have varied the legal structure, custody arrangements and redemption mechanics — and that variation is the core investor takeaway.
Key structural differences compared with allocated bullion
- Legal claim: Allocated bullion ownership is typically direct — the owner’s name on vault records for specific bar serial numbers. Many tokenized products instead create a contractual claim against the issuer or a custodial trust rather than direct ownership of specific bars.
- Redemption mechanics: Allocated bars can often be redeemed physically (subject to minimums and assay fees) through the vault provider. Tokenized products frequently impose minimum redemption amounts, KYC/AML steps, and processing windows that differ materially from straightforward bullion redemptions.
- Custody and audit: Both models rely on vaults and insurance, but tokenized issuers vary in audit frequency, proof-of-reserves practices and whether custodians are regulated — due diligence is essential.
- Transfer settlement: Token transfers can settle on-chain instantly (subject to blockchain throughput and exchange execution), while physical transfers or ETF transactions have traditional settlement cycles.
Liquidity and price formation: token markets vs physical markets
Liquidity in tokenized gold comes in two layers: the secondary-market liquidity on cryptocurrency exchanges or trading platforms, and the off-chain liquidity tied to physical redemption pathways. That duality creates specific dynamics:
- On-chain liquidity can be shallow and fragmented. Many tokenized gold tokens trade on a subset of crypto venues with variable order-book depth. During periods of market stress, bid-ask spreads can widen materially relative to major gold ETFs or spot marketplace spreads.
- Arbitrage between token price and underlying gold exists but is constrained. When a token trades at a persistent premium or discount to spot, arbitrageurs may step in — but their ability to correct the spread depends on efficient, cost-effective redemption and the issuer’s rules. High minimum redemptions, withdrawal fees, or jurisdictional frictions can prevent effective arbitrage, allowing persistent mispricing.
- Price discovery remains anchored to global spot and futures markets. Token markets tend to follow LBMA spot and major futures benchmarks, but tokenized instruments can temporarily diverge due to crypto market flows and liquidity shocks.
Costs and fees: a practical comparison
Costs for holding exposure differ by model and must be compared on a total-cost basis, not just headline fees.
- Allocated bullion: Typical costs include storage, insurance and vault handling. For many institutional and retail allocated services, these aggregate to a storage fee in the range of low‑to‑mid tens of basis points annually for large holdings, rising for smaller accounts or specialty custody.
- Physically backed ETFs: ETFs such as SPDR Gold Shares or iShares Gold Trust charge expense ratios (commonly 0.1%–0.5% depending on the fund), plus potential trading spreads when buying or selling shares.
- Tokenized gold: Fee layers can include issuance/redemption fees, on-chain transaction fees, custody costs embedded in issuer economics, and exchange spreads. In some cases token issuers position lower headline fees but implicit costs (wider bid‑ask spreads, withdrawal costs, or custodial pass‑through charges) can make them comparable or, on net, more expensive.
Counterparty, custody and regulatory risk
Tokenized products concentrate several risks:
- Issuer credit and operational risk: Tokens are often claims against an issuer or custodian. If the issuer becomes insolvent, token holders’ legal claims differ depending on the legal wrapper — some are direct property rights, others unsecured claims.
- Custodial transparency: Verify how often audits are performed, who conducts them, and whether the custodian is regulated in a jurisdiction with enforceable protections. Some token issuers publish third‑party attestations; frequency and scope vary.
- Smart contract and platform risk: Tokens rely on smart contracts and exchanges; bugs, hacks or platform insolvency can impair access even if the underlying metal is secure.
- Regulatory uncertainty: Jurisdictions differ in how they treat tokenized commodities for custody, taxation and consumer protection. In some markets tokenized gold may be treated like crypto assets, with different insolvency and tax consequences than physical bullion.
Checklist for gold investors considering tokenized gold
Before allocating capital to tokenized gold, run a structured due diligence checklist:
- Confirm the legal nature of your claim: direct allocated ownership vs. contractual claim.
- Check redemption terms and minimums, both quantitative and operational (KYC, processing times, physical delivery options).
- Verify custodian identity, regulations they operate under, and frequency of independent audits or reserves attestations.
- Review fee schedule: issuance, redemption, custody, on-chain gas costs, and expected bid-ask spreads.
- Assess market depth where the token trades and test liquidity during stressed market scenarios.
- Understand tax and reporting treatment in your jurisdiction and how transfers or redemptions are treated.
- Confirm insurance coverage specifics: named perils, limits, and whether insurance attaches to segregated bars.
How to use tokenized gold in a diversified gold allocation
Tokenized gold can play useful roles, but it should not be treated as interchangeable with allocated bullion without careful analysis. Practical allocation approaches:
- Trading sleeve: Use tokenized gold for short-term trading or tactical exposure where on-chain settlement and exchange access are advantages.
- Paper allocation with exit plan: Hold tokenized positions for liquidity and lower apparent costs, but maintain a clear redemption pathway if you intend to convert to physical bullion in a crisis.
- Core physical allocation: For investors prioritizing guaranteed physical possession and legal title, allocate a core share to allocated bars/coins held with reputable vaults and trustees.
- Hybrid approach: A mix — core allocated bullion, complemented by liquid token positions for rebalancing and tactical moves — balances custody certainty and tradability.
Conclusion: not a one‑size‑fits‑all decision
Tokenized gold has matured into a meaningful corner of the market by late 2026, offering rapid settlement, programmable exposure and easy access on certain trading venues. But structural differences in legal claims, redemption mechanics, custodial transparency and liquidity profile mean tokenized gold is not a drop‑in replacement for allocated bullion. For buy-and-hold investors who prize direct title and predictable conversion to physical metal, allocated bullion still provides ironclad clarity. For traders and investors who prioritize liquidity and on‑chain convenience, tokenized gold can be compelling — provided the investor performs rigorous due diligence on issuer structure, custody, fees and regulatory risks.
In practice, many prudent portfolios now blend instruments: an allocated physical core to assure title and delivery options, and a tokenized or ETF sleeve to provide tactical flexibility. The precise split depends on your objectives, timeline, tax environment and tolerance for counterparty or technical risk — and those are decisions every serious gold investor should document before adding tokenized products to their holdings.