Overview
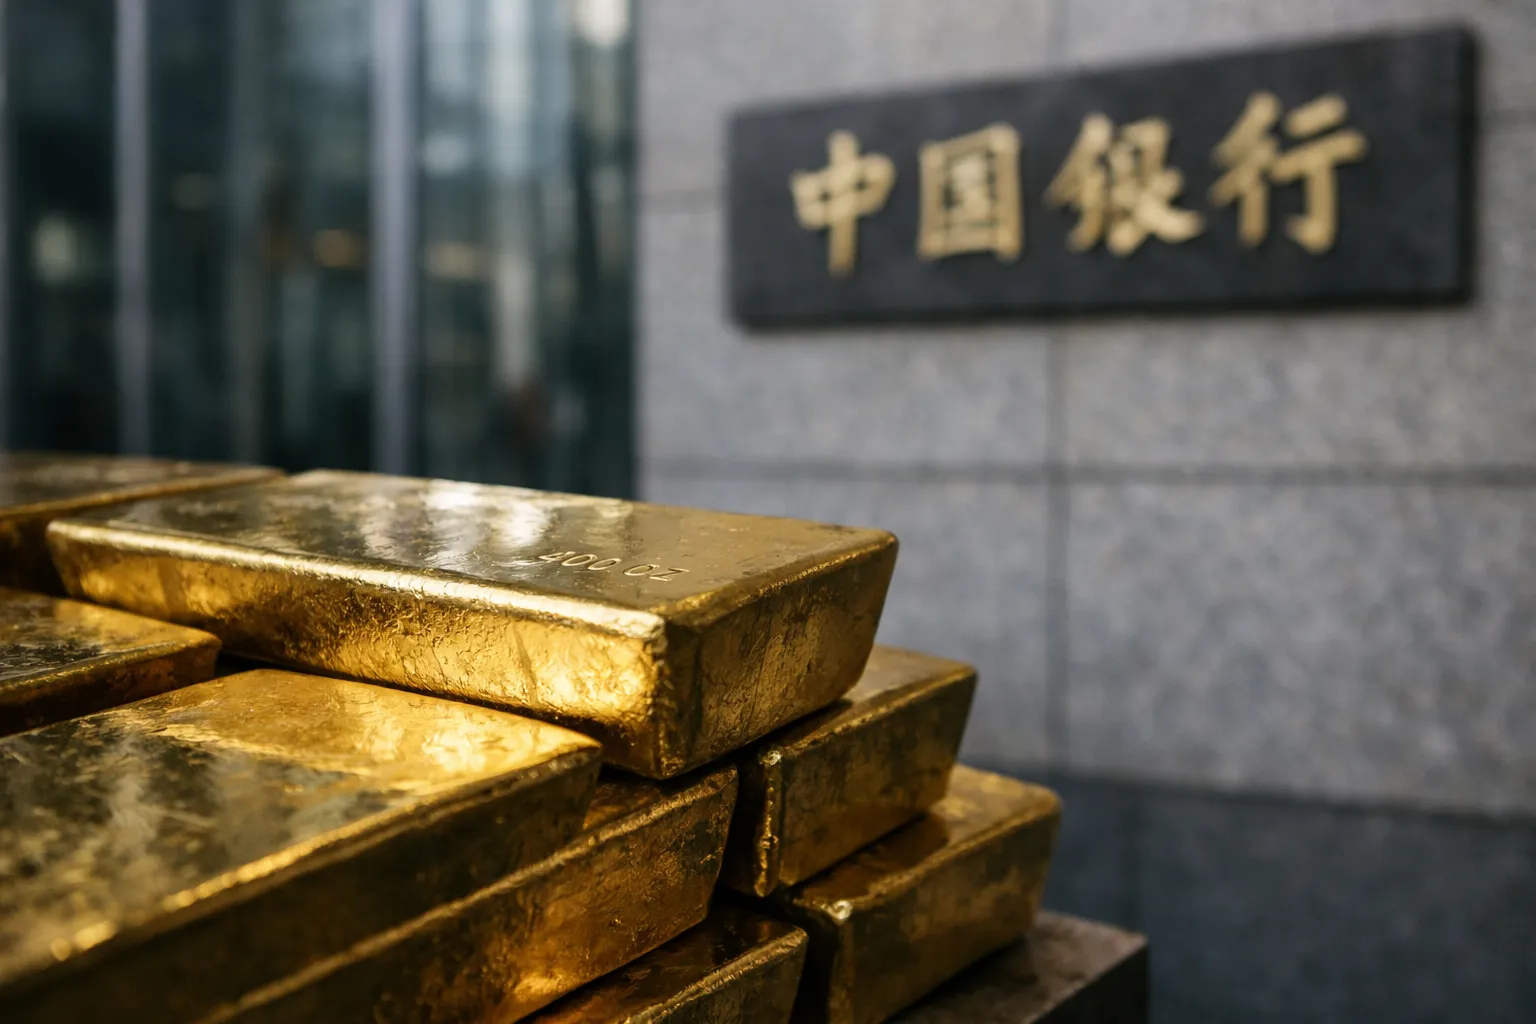
As of September 2026, China's deliberate accumulation of gold continues to reshape physical flows, regional pricing and market mechanics. This update synthesizes developments since August 2026, highlights fresh indicators to watch, and gives actionable, operational guidance for allocators, traders and physical holders navigating a market where where metal sits matters as much as the dollar.
Background: why China’s buying still matters
China remains both a major producer and a dominant source of demand for physical gold. Beijing’s framing of gold as a strategic reserve asset — tied to financial resilience, renminbi internationalization and diversification of official holdings — has persisted through 2026. Because much of the buying is executed through state channels, domestic exchanges and institutional accumulation rather than solely via western ETFs, the pattern of flows has an outsized influence on where metal is stored and how quickly it can be redeployed into global markets.
What changed since August 2026
- Flows stayed biased to Asia: Through August 2026, Chinese exchange withdrawals and Hong Kong customs data continued to point to net inflows into Chinese custody. Asian exchange withdrawals have now outpaced their long‑term averages for most months of 2026, sustaining regional tightness.
- London inventories remain under pressure: LBMA vault reports in 2026 show a persistent thinning relative to the start of the year, supporting higher Asian premiums at times when shipments are announced or executed.
- Clearing and settlement upgrades: Market participants report smoother but more tightly controlled cross‑border settlement processes after regulatory adjustments implemented in mid‑2026. The effect: lower turnover speed on repatriated metal and greater certainty regarding provenance — but also higher short‑term delivery frictions.
- Policy context tightened: Public statements and small, incremental reserve disclosures in 2026 reaffirmed the strategic rationale for accumulation. That reduces the likelihood of abrupt, price‑sensitive liquidation by official holders.
Data and evidence investors should monitor now
Direct, timely disclosure of official Chinese purchases remains limited. Practical investors should synthesize multiple proxies; those that proved most informative through summer 2026 include:
- SGE withdrawals and interbank transfer volumes: Persistent above‑average withdrawals on the Shanghai Gold Exchange indicate metal moving into domestic custody or industrial channels.
- Hong Kong customs/net imports: Monthly trade data remains the most transparent statutory record of metal crossing into Greater China and often precedes changes in domestic inventories.
- LBMA weekly vault holdings: Declines or stagnation in London inventories correlate with episodes of Asian premium widening and tighter physical availability in western hubs.
- Local dealer premiums and bid/ask spreads: Real‑time dealer quotes in Hong Kong, Shanghai and Singapore are the fastest market thermometer for regional scarcity.
- Futures/forwards basis and financing spreads: COMEX and Asian forwards (SGE/TOCOM-linked products) show divergent basis behavior when large shipments are looming — watch basis moves relative to cross‑rates and short‑term funding spreads.
Multiple perspectives
Chinese authorities frame accumulation as long‑term strategic diversification; public communication emphasizes resilience rather than speculative timing. That suggests official buying may continue even without sharp spot moves.
Asian bullion dealers and vault operators report sustained demand for allocated, delivery‑ready metal, and note longer lead times for certified cross‑border deliveries due to enhanced provenance and compliance checks introduced in 2026.
Western markets and ETF managers acknowledge intermittent decoupling between paper prices (COMEX/LBMA) and Asian physical conditions. Some ETF issuers have expanded regional vault options or clarified delivery mechanisms to better align with client needs.
Miners and hedgers say that Asia‑centric pricing power has risen for producers selling into regional offtake channels; several mid‑tier producers have negotiated higher premiums for Asia‑delivered concentrates and doré.
Implications — what this means for investors
- Regional premiums likely to persist: Expect episodic widening of Asia‑West spreads when shipments are executed. For physical buyers in Asia, factor in higher all‑in costs for delivery‑ready allocated metal.
- Paper vs physical divergence: ETFs and futures can still provide exposure, but may understate local physical scarcity in Asia. For exposure closely tied to Asian physical markets, consider vehicles with regional vaulting and physical delivery options.
- Operational risk rises: Single‑jurisdiction custody exposes holders to access and delivery risk if cross‑border flows accelerate. Multi‑jurisdiction custody reduces this operational concentration risk.
- Hedging mismatch for producers: Producers hedging Asia‑facing sales with western futures should reassess hedge ratios and consider local forwards or OTC solutions priced off Shanghai/Hong Kong benchmarks.
- Trading and margin risk: Basis dislocations can create opportunities, but also sudden margin calls; update stress tests and financing plans to reflect slower physical mobility and episodic backwardation in Asian markets.
Actionable checklist — what to do right now
- Build a monitoring dashboard: combine SGE withdrawal series, Hong Kong customs net imports, LBMA vault trends and dealer premium feeds for early warning of regional tightness.
- Diversify custody: where practical, split allocated holdings across at least two jurisdictions (e.g., London + Hong Kong or Shanghai) to preserve optionality for delivery and sale.
- Update risk models: add scenarios for extended Asian backwardation and increased cross‑regional funding costs; run margin and settlement stress tests on leveraged positions.
- Prefer delivery‑capable ETFs or regional vault options if you need close exposure to Asian physical pricing.
- For producers and hedgers: complement western futures with local forwards or OTC contracts linked to Shanghai/Hong Kong benchmarks to avoid basis mismatch.
Scenario framing: three paths for the remainder of 2026
- Baseline: Continued, measured accumulation by Chinese buyers with persistent but manageable Asian premium pressure. Outcome: structural support for gold prices and continued cross‑regional spreads.
- Accelerated accumulation: A policy push (reserve revaluation or explicit RMB‑internationalization step) leads to a sustained increase in buying. Outcome: notable depletion of western inventories, recurring backwardation in Asia and higher execution costs for futures players.
- Shock or policy discontinuity: A geopolitical shock or abrupt capital‑account action creates a spike in domesticization of foreign‑held bullion. Outcome: temporary settlement freezes, material delivery bottlenecks and elevated counterparty risk.
Outlook — what to watch next
In the short term, the pace and visibility of SGE withdrawals and Hong Kong customs flows will be the most actionable indicators. Over coming months, also watch: (1) LBMA weekly vault reports for London inventory trajectories; (2) any incremental public disclosures from China's monetary authorities or audited reserve reports; and (3) dealer premium behavior in Hong Kong and Shanghai — these move fastest and often pre‑empt official statements.
Conclusion
Through September 2026, the structural story that emerged in mid‑2026 — strategic, diversified Chinese accumulation plus reserve rebalancing among several emerging economies — remains intact. That means investors must think beyond price direction and incorporate physical location, custody and settlement dynamics into portfolio and trading decisions. The practical steps above — diversified custody, enhanced monitoring and updated stress tests — offer a defensible operational playbook for navigating a market where physical availability in Asia can materially alter price discovery and execution costs.
Frequently asked questions
Is China still buying gold in September 2026?
Yes. Although China does not publish a continuous line‑item of official monthly purchases, a constellation of indicators — SGE withdrawals, Hong Kong customs net imports and thinning LBMA London inventories — point to continued net accumulation through mid‑2026 into September. The purchases appear strategically motivated rather than purely price‑driven.
How quickly can gold repatriated to China be re‑exported to western markets?
Repatriation followed by re‑export has become slower in 2026 owing to tighter provenance checks and logistics constraints. While metal can still be moved, expect longer lead times and higher compliance costs; rapid round‑trip arbitrage is less reliable than in prior years.
Should retail or private investors move physical holdings to Asia?
Not necessarily. For most private investors, a balanced approach matters: diversify custody across jurisdictions to reduce access risk, but weigh higher and variable premiums in Asia against the benefits of proximity. Ensure vault operators are reputable, allocated metal is fully segregated, and you understand redemption and delivery procedures.
Will ETFs protect me from regional physical dislocations?
ETFs provide efficient price exposure, but they can temporarily lag local physical conditions in Asia if regional tightness is pronounced. If you need exposure that reflects Asian physical scarcity, prefer ETFs with regional vault options or delivery mechanisms aligned to Hong Kong/Shanghai custody.
What immediate data points should a trader watch intraday?
Monitor dealer premium feeds in Hong Kong/Shanghai, SGE withdrawal notices, LBMA vault updates, and short‑term funding spreads. Rapid moves in basis between COMEX and Asian forwards often precede physical arbitrage opportunities — but execution risk and margin implications require caution.