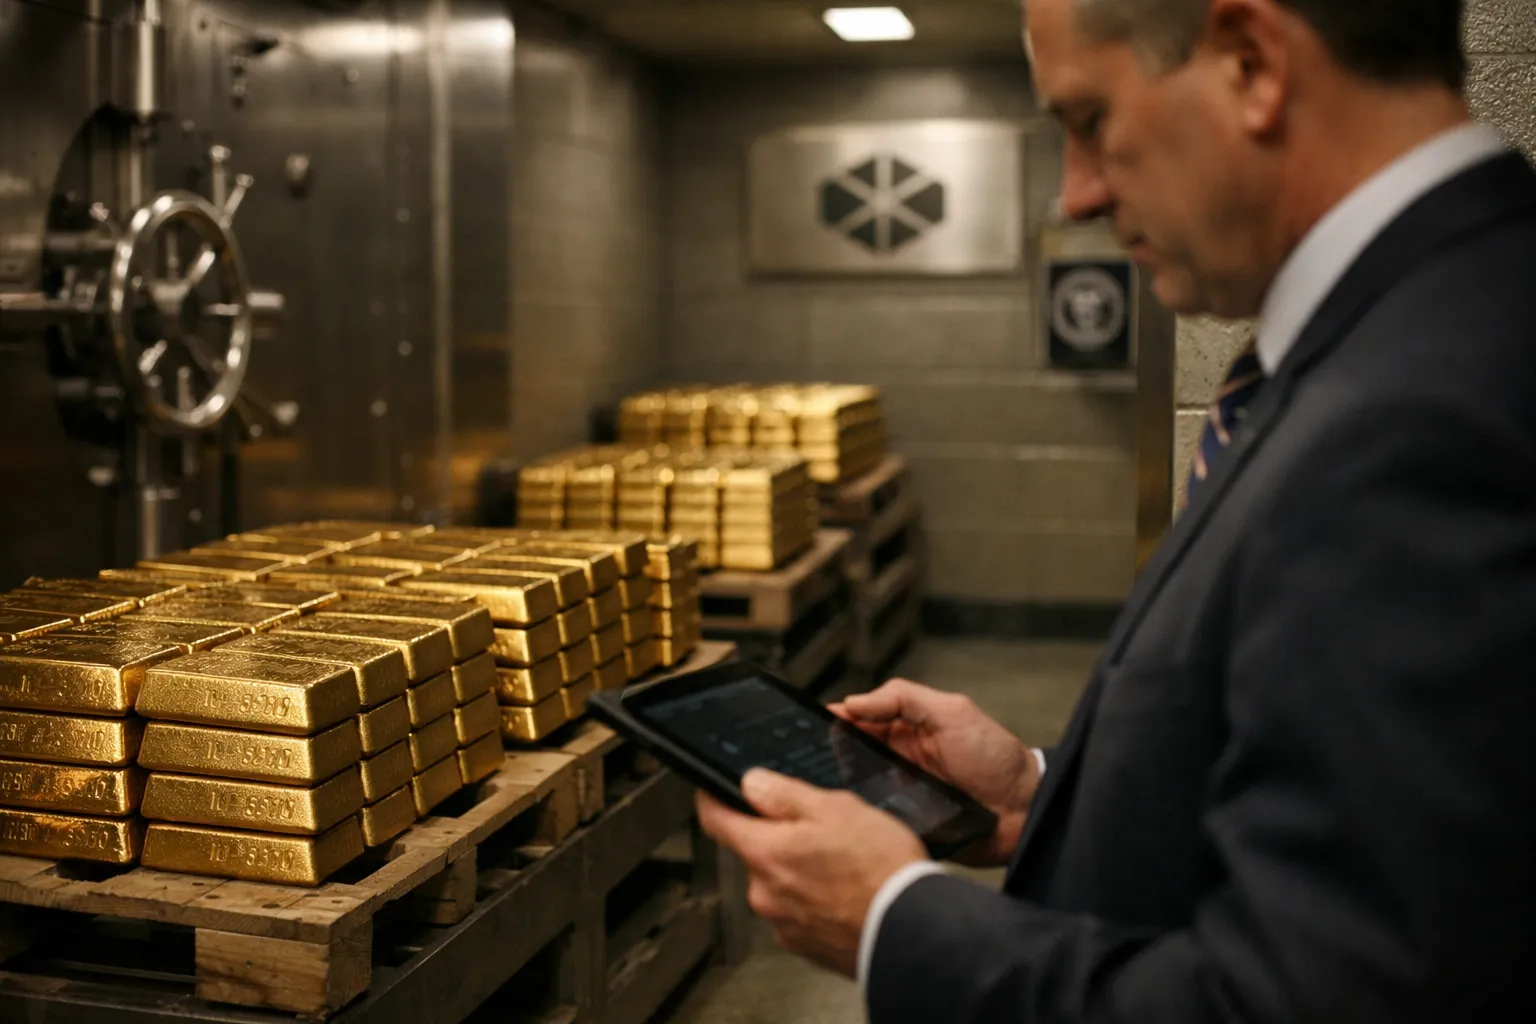
Singapore’s Monetary Authority (MAS) has approved a regulated pilot that permits banks and licensed logistics firms to offer retail allocated-gold custody services, a move that could reshape how private investors access physically allocated bullion across Asia. The pilot—announced in July 2026 and set to run for 12 months—allows participating institutions to combine traditional vault storage with a digital client interface, standardized audit trails and insured transit services.
What the pilot permits and who is involved
Under the MAS framework, licensed banks may partner with regulated precious-metals logistics providers to offer retail clients fully allocated gold accounts. Participating institutions must meet strict requirements on segregation, independent auditing, insured transit and real-time holdings reporting. The pilot is limited to defined product sizes—typically 1‑gram bars up to kilo bars—and to retail clients resident in jurisdictions that permit cross-border custody under Singapore law.
Consortium participants named in the initial rollout include a major Singapore-headquartered bank and an international logistics firm with a global vault network. Both firms will be required to publish transparent fee schedules and to employ third-party auditors to verify allocated holdings at least quarterly. MAS has also mandated mandatory insurance coverage that follows the bullion during transit as well as in-storage.
Why MAS moved now
MAS says the pilot balances innovation and investor protection. Regulators cited growing retail demand for physically allocated gold accessible through bank channels, concerns about custody and provenance in some tokenized-gold products, and the need to establish clear standards for segregation and auditability. By piloting within the regulated banking environment, MAS aims to create a playbook that preserves physical allocation standards while expanding retail access.
Practical implications for gold investors
The pilot introduces several tangible changes investors should track closely.
- Easier retail access to allocated gold: Bank-fronted custody removes barriers such as minimum holdings and corporate-only vault access. Retail investors can potentially open allocated accounts through standard bank onboarding.
- Reduced basis risk vs. ETFs: Allocated holdings avoid certain counterparty and creation/redemption mechanics of ETFs, which can matter in periods of market stress. However, allocated accounts may carry different liquidity profiles (see below).
- Fee transparency: MAS’s requirements for published fee schedules could compress spreads and reduce unexpected charges that have plagued some private vault accounts.
- Insurance and audit standards: Standardized insurance and mandated independent audits increase custody certainty—important for investors who prioritize physical ownership claims.
Liquidity, premiums and market structure
Wider retail access to allocated gold via banks could have modest but measurable effects on local spot premiums and secondary-market liquidity.
- Spot-premium compression in Singapore: As more retail funds flow into allocated accounts priced against local spot, dealers may need to narrow buy-sell spreads to remain competitive.
- Secondary market liquidity: Allocated accounts are not directly tradable like ETFs; investors liquidate either by instructing the custodian to sell in the wholesale market or by requesting physical delivery. That process can extend settlement times and affect liquidity during spikes in demand.
- Flow divergences with ETFs: If retail demand shifts from gold ETFs to bank custody, ETF creation/redemption dynamics could change, potentially reducing arbitrage flows that currently keep ETF prices tightly aligned with spot.
Risks and open questions
While the pilot improves some custody concerns, it raises practical and regulatory questions investors should monitor.
- Cross-border transfer restrictions: The pilot allows cross-border custody only where legal frameworks permit. Investors seeking to shift holdings between vaults in different jurisdictions may face legal and tax hurdles.
- Deliverability and minimums: Some banks may impose minimums for physical delivery or charge steep handling fees, reducing the practical option of home or courier delivery for retail clients.
- Counterparty concentration: A bank-led model changes the counterparty from a specialized bullion dealer to a regulated bank; that reduces certain risks but concentrates exposures to banking-system issues.
- Tax and reporting implications: Allocated accounts held through a bank may generate different reporting and tax outcomes compared with offshore vaults or ETFs. Investors should consult tax advisors to understand capital gains, wealth reporting and potential VAT/goods-and-services implications.
What to watch during the pilot
Gold investors should track several near-term indicators that will reveal whether the pilot achieves MAS’s aims:
- Adoption metrics: number of retail accounts opened and average account sizes.
- Fee and premium trends: whether banks offer competitive custody fees and whether local spot premiums narrow.
- Audit outcomes: transparency of quarterly third-party audit reports and whether any discrepancies emerge.
- Operational performance: invoice-to-delivery timelines, insurance claims (if any), and customer-service resolution times for delivery or sale requests.
Bottom line
The MAS pilot marks a notable step toward mainstreaming physically allocated gold for retail investors within a regulated banking context. For gold enthusiasts, the program promises improved custody standards, clearer fee structures and easier access. But investors should weigh the trade-offs: allocated accounts enhance physical ownership certainty yet can change liquidity and tax profiles versus ETFs or offshore vaults. During the 12-month pilot, careful attention to audit reports, fee transparency and real-world settlement performance will be essential to assess whether bank-backed allocated custody becomes a durable option for retail gold portfolios.