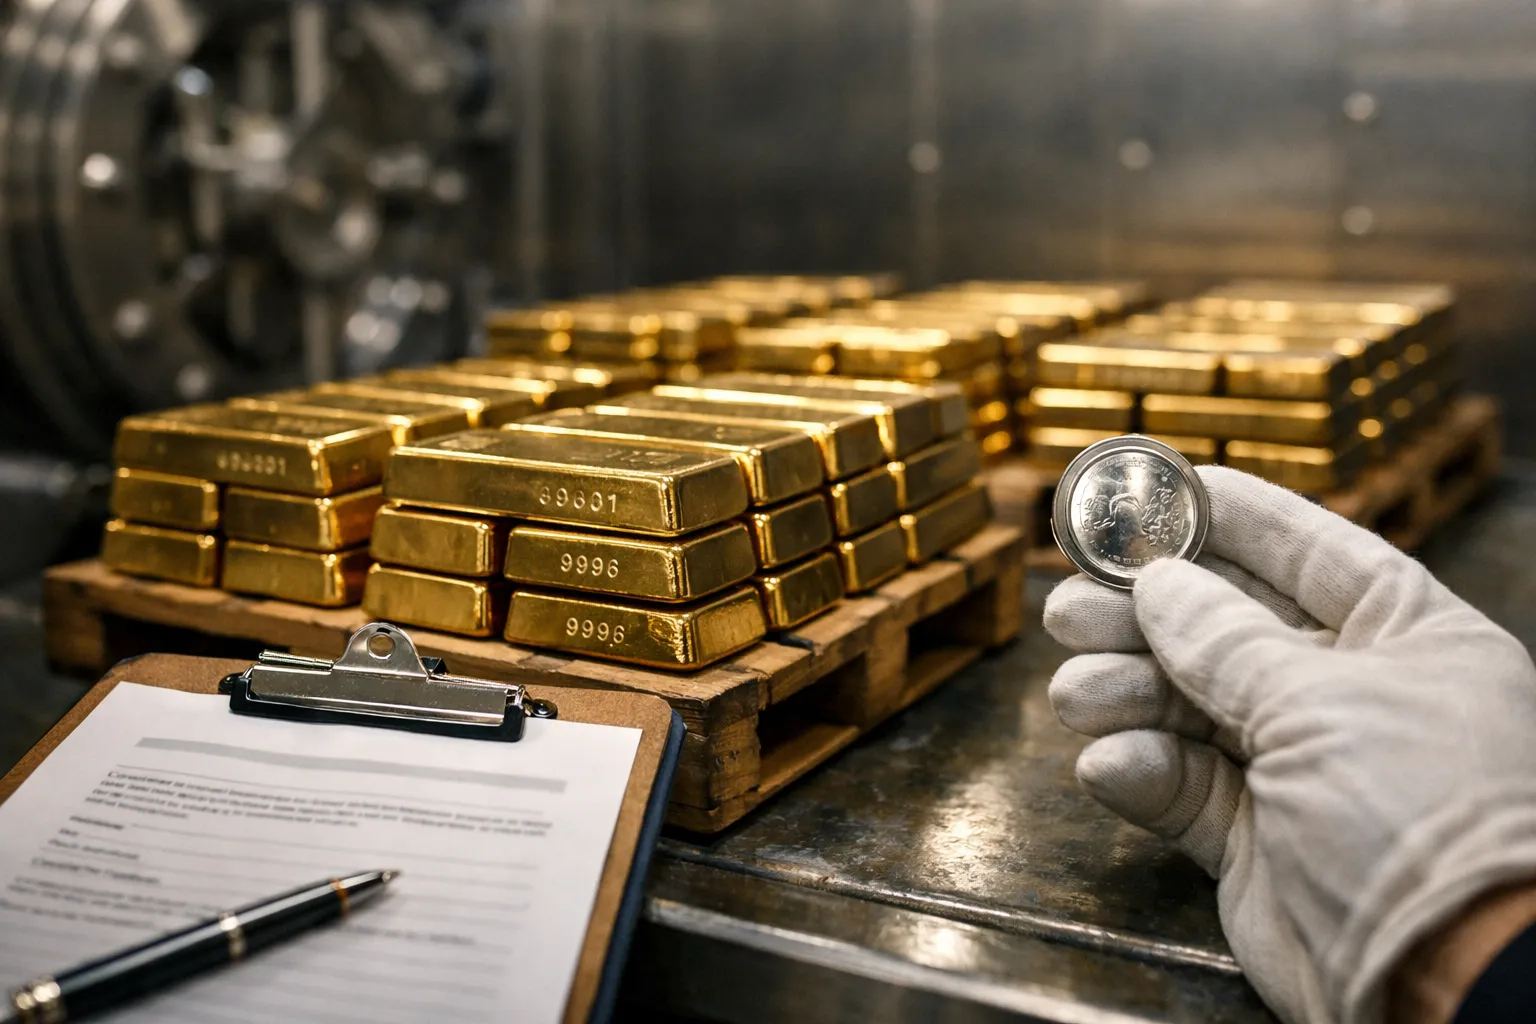
For serious gold investors in 2026, physical bullion remains a core store of value — but “physical” covers a wide set of choices: spot‑sensitive coins and ETFs for liquidity, large bars in secure vaults for low cost, and heir‑ready pieces held for legacy. This guide walks you, step by step, through designing, buying, storing, insuring and exiting a practical 3‑tier physical gold portfolio that balances liquidity, cost efficiency and estate planning.
Why a 3‑Tier Approach?
Rather than treating all physical gold the same, a 3‑tier framework aligns different investor objectives and operational needs:
- Tier 1 — Liquidity: Quick access for market moves or cash needs (coins, small bars, and gold ETFs).
- Tier 2 — Core Allocated Bullion: Low‑cost, allocatable physical reserved for medium‑to‑long horizons (kilogram bars, 400 oz bars, allocated vault storage).
- Tier 3 — Estate & Numismatics: Heir‑friendly pieces and collectible coins maintained for legacy value and family transmission.
This separation clarifies buying venues, custody methods, insurance, tax planning and exit strategies for each bucket.
Step 1 — Set Target Allocation and Objectives
Start by defining your overall gold allocation and the role each tier plays. Example allocations are illustrative — adjust to risk appetite and liquidity needs.
- Conservative, long‑term holder: Tier1 5–10%, Tier2 75–85%, Tier3 10–15%
- Active tactical investor: Tier1 20–30%, Tier2 50–60%, Tier3 10–20%
- Estate / legacy focus: Tier1 5–10%, Tier2 50–60%, Tier3 30–40%
Decide practical constraints: minimum lot sizes you can afford, location preferences (domestic vs international vaults), and whether you need physical possession of any portion.
Step 2 — Buying: Where, What, and How Much
Each tier has distinct buying channels and product choices.
Tier 1 — Liquidity
- Products: 1 oz bullion coins (Krugerrand, American Gold Eagle, Canadian Maple Leaf), 1 oz bars, or immediate‑liquid ETFs (GLD, IAU — if you require strictly physical, use coins/bars).
- Where to buy: Reputable local dealers, online bullion merchants, or major exchanges for ETFs. Prioritize dealers with transparent pricing and buyback policies.
- Premiums: 1 oz bullion coin premiums typically 1.5–3.5% (varies with demand and coin). Expect higher during market stress.
- Minimums: Buy in small lots that match your liquidity target — e.g., a $10k liquidity bucket could be ten 1 oz coins plus cash/ETF exposure.
Tier 2 — Core Allocated Bullion
- Products: 1 kg bars, Good Delivery 400 oz bars, or allocated bar batches stored in professional vaults.
- Where to buy: Authorized refiners, London market dealers, or institutional platforms that offer allocated storage.
- Premiums: Larger bars reduce premiums — 1 kg bars often 0.6–1.5% above spot; 400 oz bars can approach 0.2–0.6% for large trades.
- Purchase sizing: Aim to buy in sizes that align with storage minimums and transport economics (many vault custodians have minimums of $25k–$100k).
Tier 3 — Estate & Numismatics
- Products: Proof coins, limited‑edition sovereigns, or designated heirloom ingots. Consider pieces with strong provenance and low spread between buy and sell prices.
- Where to buy: Mint direct sales, reputable numismatic dealers, or auction houses for rare items. Obtain certificates and documented provenance.
- Premiums & liquidity: Expect higher premiums and lower day‑to‑day liquidity. These assets are chosen for transmissibility and cultural value, not trading speed.
Step 3 — Custody & Storage Choices
Storage decisions drive recurring costs, security risk, and ease of transfer. Match custody to the tier.
Tier 1 — Home, Safe Deposit, or Local Dealer
- Home storage gives immediate access but requires a high‑quality safe, security measures, and specialized insurance riders.
- Bank safe deposit boxes are low‑cost but limited access hours and offer no transport or insurance by default.
- Local dealer consignment works if the dealer provides insured vaulting and transparent access policies.
Tier 2 — Professional Allocated Vaults
- Allocated storage (segregated bars with serial numbers) is recommended for the core. Providers include global vault operators in Zurich, Singapore, London and other financial hubs.
- Typical storage fees (2026 market norms): ~0.12%–0.6% of value annually for allocated vaulting, depending on location and service (lower for large institutional accounts).
- Insurance and audits: Confirm independent annual audits and insured replacement value. Ask about unallocated vs allocated distinctions and operational proof mechanisms.
Tier 3 — Specialized Custody & Estate‑Ready Solutions
- Consider a combination of safe deposit for immediate access to heirs and a professional vault for long term security with clear chain‑of‑title documentation.
- Store certificates, wills, and transfer instructions with your attorney and a secondary secure location.
Step 4 — Insurance, Audits and Recordkeeping
Insurance and provenance matter more as amounts grow.
- Insurance: Expect commercial insurance to add ~0.10%–0.50% p.a. depending on location, risk profile and whether the vault already carries replacement coverage.
- Audits & reporting: Insist on quarterly or annual independent audits for allocated holdings. Request serial numbers, assay certificates and chain‑of‑custody reports.
- Recordkeeping: Maintain invoices, certificates, and clear estate instructions (including digital copies stored separately). Record who is authorized to access and transfer holdings.
Step 5 — Costs, Example and Running Numbers
Estimate total carrying costs (annual) and one‑off buy/sell costs to compare strategies. Below is a practical example using round numbers.
Illustrative Example — $100,000 Starting Capital
- Allocation: Tier1 10% ($10,000), Tier2 70% ($70,000), Tier3 20% ($20,000).
- Buy costs:
- Tier1: Ten 1 oz coins, average premium 2.5% → buy cost ≈ $10,250.
- Tier2: 1 kg bars, average premium 1.0% → buy cost ≈ $70,700.
- Tier3: Proof coins/numismatic pieces with average premium 8% → buy cost ≈ $21,600.
- Annual holding costs:
- Tier1 (home insurance or safe deposit): ≈ 0.2%–0.4% → ~$30–$40 p.a. on $10k.
- Tier2 (allocated vault + insurance): 0.25% (storage) + 0.15% (insurance) = 0.40% → ~$280 p.a. on $70k.
- Tier3 (higher insurance/provenance storage): ~0.5% → ~$100 p.a. on $20k.
These rough estimates show how Tier2's low relative fees keep long‑term costs manageable, while Tier3 carries higher insurance and storage expense for heritage value.
Step 6 — Rebalancing and Triggers
Set explicit rebalancing rules and liquidity buffers.
- Calendar rebalancing: Review annually and rebalance back to target buckets within a 3–5% band.
- Event triggers: Rebalance when a bucket deviates more than 7–10% from target, or after major life events (inheritance, relocation, liquidity need).
- Liquidity buffer: Keep 1–2% of portfolio value in cash or ultra‑liquid Tier1 holdings to avoid forced sales.
Step 7 — Exit and Estate Execution
Plan exits in advance for each tier.
Tier 1 Exits
- Sell quickly to local dealers, online marketplaces, or convert ETF holdings to cash. Expect spreads/premiums to widen in stressed markets.
Tier 2 Exits
- Sell in larger lots via institutional channels or forward the metal through your custodian's buyback; plan for logistics (transport, assay) that add time and cost.
- For cross‑border sales, check customs, import/export requirements and VAT rules in destination jurisdiction.
Tier 3 Estate Execution
- Document beneficiaries and transfer instructions clearly in legal documents. Consider using a trusted executor familiar with bullion transactions or a specialized trustee.
- Provide heirs with contact details of custodians, serial numbers and certificates to speed transfers and reduce the risk of loss or disputes.
Tax Considerations — High‑Level Notes
Tax treatment varies by jurisdiction and can affect how you allocate between tiers:
- In many countries physical gold sales trigger capital gains events; holding periods and rates differ. Germany has a one‑year private sale exemption for certain precious metals; check local rules.
- In the United States, physical gold is taxed as a collectible for capital gains purposes, which often attracts a different long‑term rate than standard equities — consult a tax advisor for current rates and planning strategies.
- Recordkeeping: Keep purchase invoices, serial numbers and certificates to establish cost basis and holding period.
Practical Checklist Before You Buy
- Decide total gold allocation and the specific percentage for each tier.
- Choose dealers/refiners with verifiable credentials and transparent buyback terms.
- Confirm storage provider’s allocated status, insurance, audit frequency and proof‑of‑holding procedures.
- Obtain written custody agreements and export/import policy if using cross‑border vaults.
- Document estate instructions, trusted contacts and keep backup copies of paperwork.
- Estimate full carrying cost (storage + insurance + audit fees) and add to your expected return calculations.
Common Mistakes to Avoid
- Mixing custody types without documentation — leads to disputes over ownership and slows estate transfers.
- Underinsuring small but meaningful holdings in Tier1 (home storage) — home insurance often excludes bullion or caps payouts.
- Overconcentration in high‑premium numismatics for purposes that require liquidity.
- Neglecting to verify serial numbers and certificates for allocated holdings at purchase and in audits.
Final Thought
A disciplined 3‑tier physical gold portfolio clarifies tradeoffs and operational needs: liquidity when markets move, efficient core storage for long horizons, and curated pieces for legacy. The key actions are concrete — set allocation targets, choose the right products and custodians per tier, budget carrying costs, document provenance and estate instructions, and rehearse your exit options. Do these well and you convert gold from a vague “store of value” into a dependable, operationally robust component of your wealth plan.
If you’d like, I can produce a tailored worksheet for your specific portfolio size, preferred jurisdictions for vaulting, and a projected five‑year cost model.