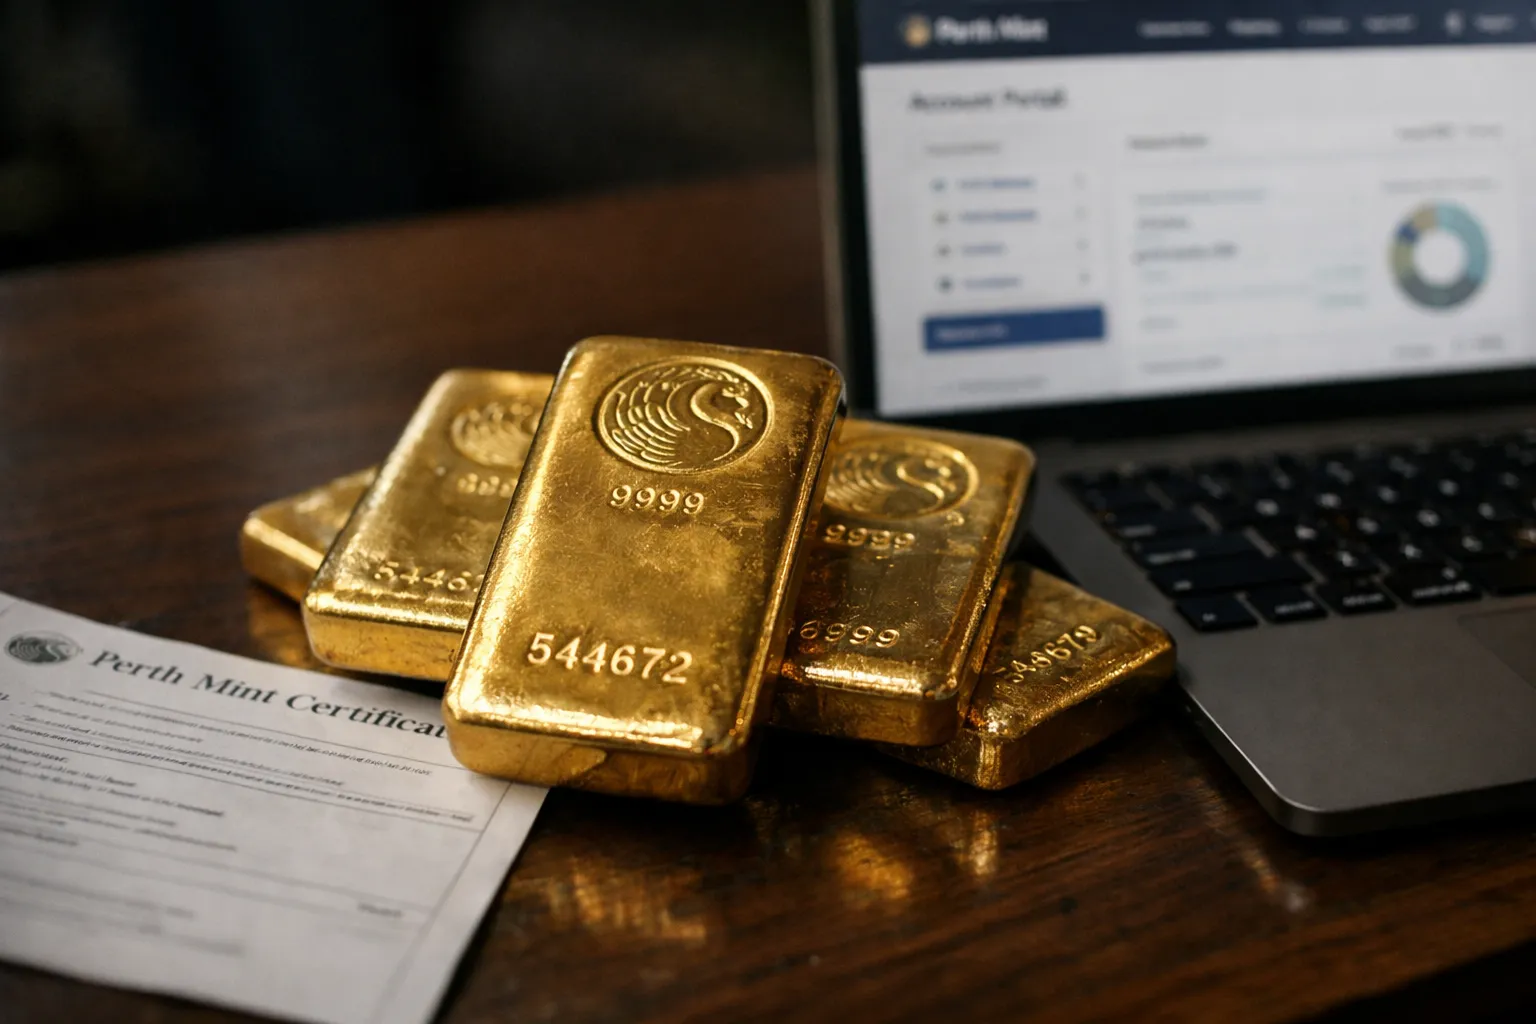
Summary: This review evaluates the Perth Mint’s allocated-gold products — principally the Perth Mint Certificate program and the depository/allocated account options — as they stand in July 2026. I assess governance and custody, convertibility to physical bars and coins, liquidity for secondary-market transactions, tax and cross-border practicalities, costs and transparency. The aim is to tell gold investors when the Perth Mint makes sense in a portfolio and where other options may be superior.
What investors are buying
The Perth Mint offers allocated precious-metal accounts and certificate programs that provide ownership of specific, serial‑numbered bars held in the Mint’s vaults. The Mint is a state-owned entity (Government of Western Australia), and its allocated products are distinct from unallocated claims or pooled ETF holdings: owners are meant to have direct title to identifiable physical metal that can, in most cases, be converted into physical delivery.
Key features — what the product includes
- Allocated, serial-numbered metal: Holdings are tied to specific bars or coins rather than an undifferentiated pool.
- Sovereign backing and brand recognition: The Perth Mint is government-owned and an internationally recognised refiner and distributor.
- Certificate and account access: Customers transact through the Perth Mint’s account platform or authorised dealers; certificates document ownership and the metal’s identity.
- Convertibility: Certificates and allocated accounts generally allow conversion into physical bars or coins, subject to minimum sizes and local redemption rules.
- Insurance and custody: Stored bullion is held in insured vaults operated under the Mint’s custody arrangements.
Pros — why investors choose Perth Mint allocations
- Credibility: Government ownership and the Mint’s long track record in refining and bullion markets provide strong institutional trust compared with many private vault operators.
- Allocated title: Direct ownership of serial-numbered bars reduces the counterparty-credit element you see with unallocated accounts or some pooled ETFs.
- Deliverability: For investors who want the option to take physical delivery in identifiable bars or coins, the Perth Mint’s convertibility is a core advantage.
- Usability for cross-border buyers: The brand is widely accepted by dealers and refiners internationally, which helps when seeking resale or delivery in other markets.
Cons and limitations
- Jurisdictional and tax complications: Holding allocated metal in an Australian government facility may complicate tax treatment, withholding, and estate planning for non‑Australian residents; investors should obtain jurisdiction‑specific tax advice.
- Costs and fee transparency: Retail investors report a mix of dealer mark‑ups, transaction charges, and custody fees; while competitively priced at scale, small holdings can be comparatively expensive once dealer spreads and account fees are included.
- Operational friction for delivery: Physical redemption has minimums and logistics (shipping, import/export rules, local dealer acceptance) that can make small redemptions impractical.
- Not an intra-day trading vehicle: Allocated accounts are designed for custody and preservation, not active trading or arbitrage — ETFs and digital markets remain superior for trading liquidity.
Liquidity and market access in 2026
In 2026 the Perth Mint remains a recognised counterparty: dealers and refiners accept its bars and certificates, which supports secondary-market liquidity. That said, liquidity is not the same as an exchange-traded product: selling typically occurs via authorised dealers, broker networks or local coin dealers rather than instant exchange trades. For large-lot institutional flows, the Mint handles sizeable trades efficiently; retail sellers should expect longer settlement windows and dealer spreads.
Security, insurance and counterparty risk
The Perth Mint’s government ownership reduces—but does not eliminate—counterparty risk. Insured custody arrangements protect against theft and loss, but investors remain unsecured creditors with respect to the Mint’s legal framework for client property: read the account terms carefully to confirm property segregation, insolvency protections and insurer limits. For high-net-worth investors, physical possession remains the ultimate risk mitigation; the Mint’s allocated model is a close proxy but not identical to storing metal in a personal safe.
Who should consider Perth Mint allocations?
- Conservative investors who prioritise allocated, serial‑numbered metal and a strong refiner/sovereign counterparty.
- Buy-and-hold investors who may want the option of physical delivery at some point, rather than traders seeking short-term liquidity.
- International investors who value the Perth Mint brand for downstream acceptance when selling or converting metal.
Who might prefer alternatives
- Short-term traders and liquidity-driven investors — choose ETFs or listed trusts for intra‑day liquidity and lower transaction turnaround.
- Investors focused on the lowest cost-of-carry for small ticket sizes — compare dealer markups, local vaults and fee schedules before committing.
- Those who require domestic custody in another jurisdiction for tax or regulatory reasons — a local allocated vault may be preferable.
Practical checklist before opening an account
- Confirm the product: certificate vs allocated account vs purchase-through-dealer and understand the legal title.
- Ask for the custody terms: where is the metal held, is it fully segregated, and who insures it?
- Request delivery rules and minimums, plus timeframes and costs for physical redemption.
- Obtain a full fee schedule, including dealer spreads, transaction fees and annual custody charges.
- Check tax and reporting implications for your residence and get written guidance if necessary.
Verdict
The Perth Mint’s allocated-gold offerings remain a strong choice for investors who prioritise allocated, identifiable metal with a long-standing sovereign-backed counterparty. They are particularly suitable for medium-to-large buy-and-hold allocations where convertibility to physical bullion is a meaningful option. For frequent traders, small-ticket investors sensitive to dealer spreads, or those who need custody in a different jurisdiction, other solutions (ETFs, local allocated vaults, or private safes) may be better.
As always in 2026’s active gold market: match the custody solution to your objectives—security, deliverability, cost and liquidity—and read the fine print before committing capital.