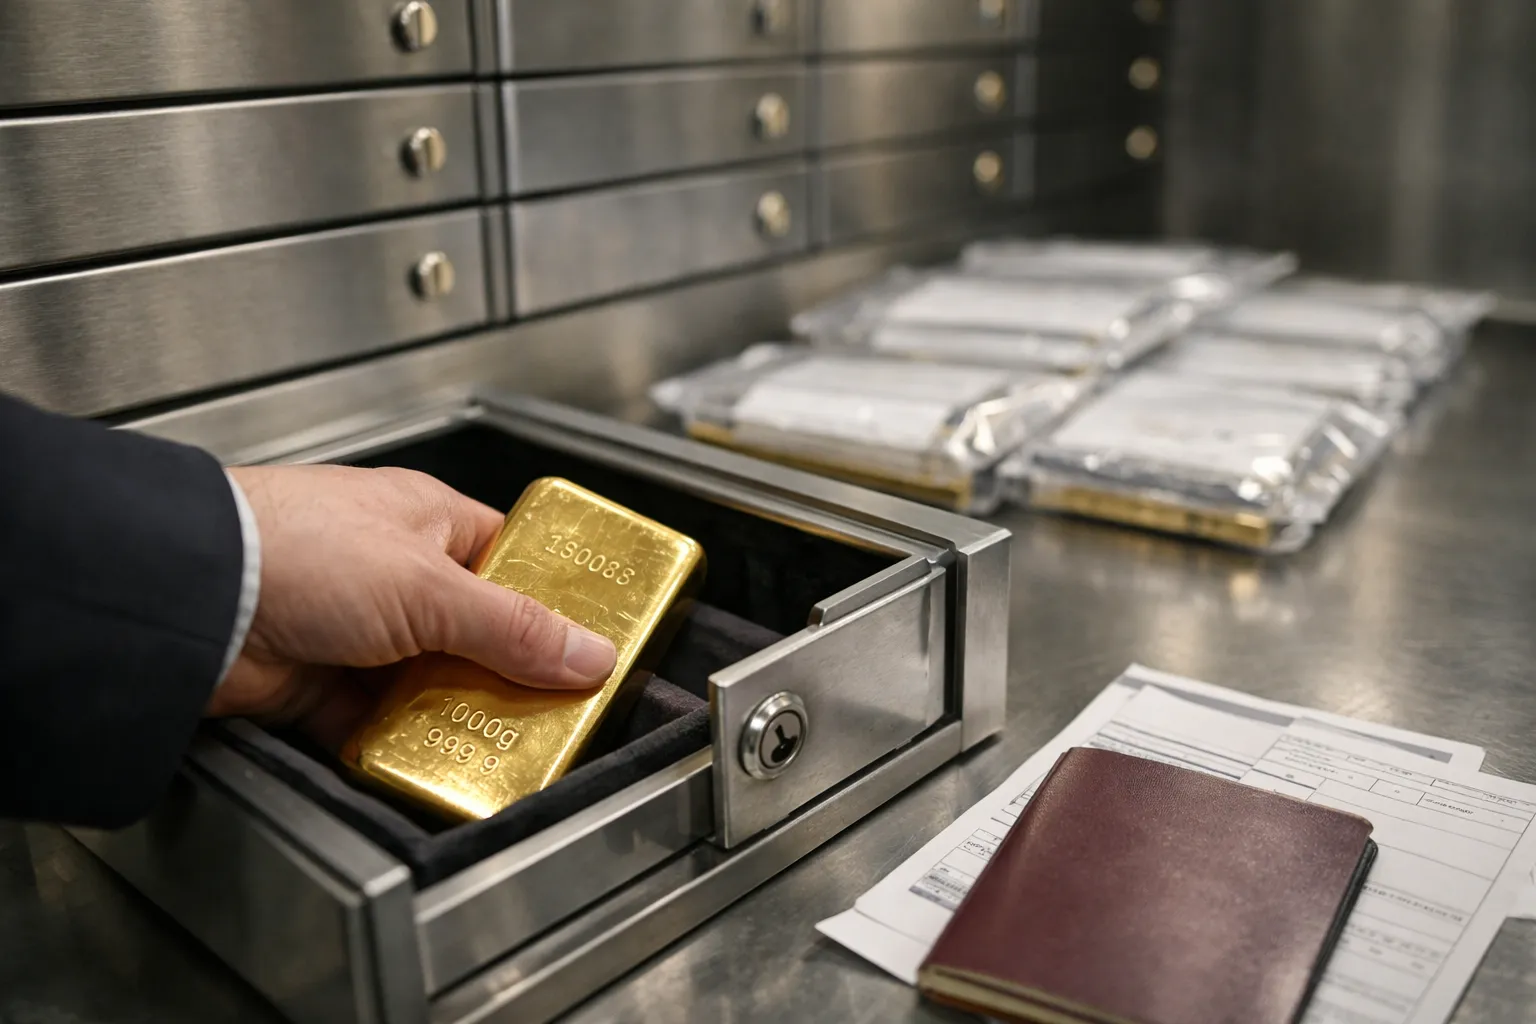
Owning physical gold across borders continues to deliver portfolio diversification, privacy and access to international markets — but since 2020 those benefits have come with steadily rising legal and compliance cost. This updated June 2026 guide shows what gold investors need to do today: defining objectives, mapping tax and reporting exposure, choosing jurisdictions and custodians, documenting legal title, arranging insured transport and bonded storage, and planning exit and succession. It is written for individual and family investors who already hold or plan to hold bullion outside their country of residence and who want concrete, verifiable steps to reduce legal, tax and operational risk.
Prerequisites / Context
Before you act, three things you should have in place:
- Tax adviser and international counsel: at minimum a short written memo from an adviser who understands cross‑border asset reporting for your tax residence.
- Up‑to‑date identification and source‑of‑fund documents: recent passport, proof of address, and original purchase invoices or bank transfer records.
- A clear objective: are you buying for easy on‑demand physical access, long‑term wealth preservation, or short‑term trading through local markets? The objective drives jurisdiction, custody type and the paperwork you need.
Why cross‑border gold ownership matters in June 2026
From 2020 through mid‑2026, tax and anti‑money‑laundering expectations have hardened. Custodians now routinely perform enhanced KYC, independent auditors expect controls evidence (ISAE 3402/SSAE 18 type reports are commonly requested), and tax authorities increasingly demand disclosure of foreign assets. At the same time, new operational options have matured: more vaults offer blockchain‑backed provenance records and “e‑vault receipts”; bonded‑warehouse networks have expanded in major hubs; and established hubs (Switzerland, Singapore, Dubai, London) remain popular because of legal certainty and liquidity. The practical result: paperwork and contractual terms matter more than ever — getting them right saves costs and prevents enforcement headaches.
Overview: the seven essential steps
- Define precise goals and constraints
- Map tax, VAT/GST and reporting obligations
- Choose jurisdiction and custodian type
- Select ownership vehicle and documentation
- Arrange insured transport and bonded storage
- Comply with reporting and audit routines
- Plan exit, repatriation and estate succession
Step 1 — Define goals, liquidity needs and risk tolerance
Before choosing a country or vault, answer these core questions and document them in a one‑page investment policy:
- Do you need immediate physical access (for collection or spending) or is liquidity via a dealer/exchange more important?
- Is the holding intended primarily as a hedge against currency/political risk, or as a short‑term trading position?
- Which taxes matter most (VAT/GST at purchase/import, capital gains, inheritance/estate taxes) and how much reporting burden are you prepared to accept?
- Do you want legal title in your personal name, or would a trust/company better serve privacy and succession goals?
- What counterparty risk do you accept: fully allocated/segregated vs pooled allocated vs unallocated metal accounts?
Why it matters: these answers determine the optimal custody model and the documentation you must insist on. If you need physical access, for example, allocate to a segregated vault close to your likely delivery point; if you prioritise tax efficiency, bonded storage and VAT planning will be central.
Step 2 — Map taxes, VAT/GST and reporting obligations
Tax and reporting mistakes cause the largest practical losses. Key checks to run and document:
- VAT/GST at purchase or import: many jurisdictions exempt qualifying investment gold from VAT, but the rules differ by product (bars vs coins), purity and whether the metal is imported into free/bonded status. Confirm the local interpretation for the specific bullion type before purchase.
- Capital gains and income tax: how disposals are taxed depends on your residence and the ownership vehicle. For example, disposals by companies or trusts can trigger corporate rates or controlled foreign company rules that individual holdings do not.
- Foreign asset reporting: custodial holdings abroad are subject to reporting in many jurisdictions. For US persons, holdings with a foreign custodian are likely subject to FBAR/FATCA and potentially Form 8938; for EU residents, national asset declarations and anti‑money‑laundering reporting obligations may apply.
- Customs duties and export controls: moving bullion physically can trigger customs formalities; bonded warehouses are commonly used to defer or avoid VAT/GST on re‑exports.
- Sanctions and export screening: custodians and shippers now screen for sanctioned counterparties; if your funds or provenance involve high‑risk jurisdictions, expect additional scrutiny or refusal of service.
Actionable step: obtain a short written tax memo from your international tax adviser that outlines VAT/GST treatment, capital gains exposure, reporting obligations and whether the proposed custody structure triggers controlled‑foreign‑company, wealth tax or exit tax rules in your residence.
Step 3 — Choose jurisdiction and custodian type
Jurisdiction selection remains a balance of legal certainty, tax environment, custodian reputation and practical logistics. Commonly used hubs in 2026 include Switzerland, Singapore, Dubai, the UK (London), and specific EU vault clusters (Amsterdam, Frankfurt). Consider:
- Property law and creditor protections — does the law recognise segregated ownership and protect it in insolvency?
- Custodian licensing, transparency, and whether the vault operator publishes ISAE 3402 or equivalent auditor reports.
- VAT/GST treatment, and availability of bonded warehousing linked to national customs systems.
- Operational access to local bullion markets and refiners (important if you plan to sell locally).
- Reputation, insurance arrangements, and frequency of independent inventory audits.
Custody models and the trade‑offs:
- Allocated, segregated storage: serialised bars/coins under your name — lowest counterparty risk, higher fees, strongest evidence of title.
- Allocated, pooled (census) storage: your metal is identified in the facility but kept in pooled stacks — lower fees than full segregation but still stronger than unallocated.
- Unallocated metal accounts: you hold a contractual claim on a pool — low cost but treated as a credit exposure to the custodian and not recommended for long‑term preservation without strong counterparty credit support.
Actionable step: request the custodian’s bailment/custody agreement, ISAE 3402 (or equivalent) audit report, insurance schedule (including war/terrorism exclusions), segregation policy and any sub‑custody arrangements. Put these on a secure file in advance of transfer.
Step 4 — Select ownership vehicle and document title
Ownership vehicle choices materially affect tax and reporting. Typical options:
- Direct ownership: simplest but transparent — often triggers direct reporting obligations in your tax residence.
- Family holding company or trust: useful for succession and privacy but can attract CFC rules, extra reporting or higher effective tax rates depending on jurisdiction.
- Nominee arrangements: provide privacy but increase legal complexity and potential for disputes — ensure nominee agreements are robust and lawful.
Minimum document checklist to obtain before or at transfer:
- Original purchase invoice and assay/certificate
- Vault receipt clearly stating allocated/segregated status and serial numbers
- Signed custody/bailment agreement and the custodian’s insurance certificate
- Proof of identity and source‑of‑fund documentation (KYC/AML)
- Any bonded‑warehouse receipt or customs documentation if shipped under bond
Why the paperwork matters: in disputes or audits, a signed, serialised vault receipt and custody agreement are the documents that prove ownership and the terms that determine remedies.
Step 5 — Insured transport, bonded storage and VAT timing
Transport and customs are recurrent failure points. Best practices in mid‑2026:
- Use specialist bullion shippers with declared‑value insurance, door‑to‑door tracking and strong claims records. Ask for insurer names and policy wordings — some insurers cap single‑shipment cover or exclude certain routes.
- Where VAT/GST is a concern, transfer directly into a bonded warehouse on arrival to defer or avoid tax if the metal will be re‑exported or remain under bond.
- Retain a full chain‑of‑custody file: purchase invoices, shipping AWBs, customs entries, bonded warehouse receipts and vault receipts.
- Consider staggered shipping of large holdings in tranches to limit exposure to a single transit loss or operational failure.
Actionable step: obtain written confirmation from the receiving vault that it accepts the shipment (including serial numbers) before releasing funds, and compare shipping/insurance quotes from at least two bullion logistics specialists.
Step 6 — Reporting, audits and ongoing compliance
Set up routines that avoid accidental breaches:
- Maintain a central, encrypted file with custody agreements, serialised receipts, assay certificates and proof of insurance.
- Ask custodians for annual independent reconciliation evidence (ISAE 3402, inventory reconciliation) and, where possible, arrange an independent physical inspection at least once every 3–5 years.
- Set calendar reminders for foreign asset reporting deadlines in your country of residence and for renewal dates on custody and insurance contracts.
- If you change tax residence, obtain a written exit opinion from tax counsel to understand whether deemed disposal, exit tax or reporting triggers apply.
Actionable step: produce a one‑page holdings summary (jurisdiction, custodian, serial numbers, acquisition cost, purchase date, insurance limits) and store a copy with your estate documents and with a trusted adviser or encrypted vault accessible to your executor.
Step 7 — Plan the exit: repatriation, sale and succession
Plan exits well before you need to act. Key considerations:
- Decide whether to sell in the vault jurisdiction (avoids shipping but may create local tax exposure) or repatriate physically (incurs shipping and customs but may simplify local tax reporting).
- Gather original purchase documents — customs authorities and tax offices ask for proof of original purchase price and VAT treatment when applying reliefs.
- Include vault access, custodian contact and a copy of the custody agreement in your estate plan. Executors commonly stumble over missing serial numbers or lack of authority letters.
Actionable step: create an “exit playbook” with preferred buyers, pre‑approved shipping routes, customs brokers and a timeline to sell or repatriate within an acceptable window.
Practical cost benchmarks (June 2026 typical ranges)
Costs vary by provider and jurisdiction; use these indicative ranges when comparing offers (validate with written rate cards):
- Premiums over spot at purchase: 0.7–3.5% for standard bars (1oz–1kg); 1–6.5% for common coins depending on mintage and demand.
- Allocated, segregated vaulting fees: 0.14–0.8% p.a. of value (retail minimums higher for under‑1kg lots; institutional scales lower).
- Unallocated metal accounts: lower fees (often a small monthly charge or basis point fee) but increased counterparty credit exposure.
- Shipping and insured transport: $100–$700 per shipment depending on size, route and declared value; high‑value international shipments with secure escort services cost more.
These are directional ranges — get written rate cards and confirm all fees and potential VAT/GST on top of quoted rates.
Red flags and questions to ask every custodian (updated)
- Can you inspect serial numbers and request a physical verification on demand? If not, why?
- Is storage allocated and segregated in law, not just in ledger entries? Ask for the legal basis and insolvency protections.
- Can metal be rehypothecated, lent or used in derivative books? Are there limits and notice periods?
- Who is the insurer, what are per‑item limits, and can you review the insurance policy wording (including war/terrorism exclusions)?
- Do you have an ISAE 3402/SSAE audit or equivalent and the latest independent inventory reconciliation report?
- What is the documented process and timeline for physical delivery or sale, and what fees apply on exit?
- Do you screen for sanctioned counterparties and high‑risk provenance, and could that screening block transfers or create delays?
Case example — updated
Investor B is a Canadian UK‑tax resident (dual residency planning) who wants to hold 10kg of 1kg bars to hedge currency risk and maintain private holdings while living in London. Steps taken in June 2026:
- Tax check: obtains a written memo from UK tax counsel confirming VAT exemption for qualifying investment gold on import and clarifying UK reporting obligations for foreign custodial holdings.
- Custody selection: requests ISAE 3402 report and insurance schedule from three custodians in London and two in Switzerland; chooses a segregated, allocated account in a London vault with annual inventory reconciliation and immediate delivery rights within 10 business days.
- Transport: ships via a specialist bullion logistics firm into a bonded warehouse to preserve VAT treatment until settlement; retains bonded receipts and airway bills in the file.
- Ongoing compliance: sets annual reminders to reconcile serial numbers, renew insurance, and update the one‑page holdings summary shared with the family solicitor.
- Exit planning: establishes a local buyback agreement with an approved dealer and a standby customs broker to repatriate if needed.
Common mistakes to avoid
- Accepting verbal custody terms — always get signed agreements and serialised receipts.
- Assuming tokenised gold equal to allocated physical metal — verify legal title and custodian solvency.
- Failing to secure an independent audit report or insurance policy wording — both are essential for claims or disputes.
- Not planning for sanctions or AML screening delays — expensive hold‑ups commonly occur at transfer.
- Ignoring exit planning — without it clients face high shipping costs and tax surprises when they need liquidity quickly.
Pro tips
- Split holdings across two jurisdictions to reduce single‑jurisdiction operational risk and simplify local access in emergencies.
- Stagger purchases over time to reduce market timing and single‑shipment transit risk.
- Negotiate a specific exit timeline and fee cap in your custody agreement so you won’t face open‑ended costs on sale or delivery.
- Request that your custodian append the vault receipt with chain‑of‑custody or LBMA Good Delivery references where applicable.
- For tokenised gold, insist on contractual language that proves legal title to specific serialised bars rather than a mere contractual claim.
FAQ
Do I have to report bullion held in a foreign vault to my home tax authority?
Often yes. Many countries require disclosure of foreign custodial holdings even if the metal is physically abroad. US persons should consider FBAR/FATCA rules; EU and other OECD countries have their own reporting. The correct approach is to get a short written tax memo for your specific tax residence — that memo should state which forms and thresholds apply to your structure.
Is tokenised gold the same as owning allocated physical bullion?
Not necessarily. Tokenised gold can represent: (a) a direct claim to a specific serialised bar held in a segregated account, (b) a claim on pooled physical metal, or (c) purely a financial derivative with no underlying physical commitment. Always check whether the token gives you legal title to specific metal, where that metal is stored, and whether it is fully insured and audited.
Can I avoid VAT by storing gold in a bonded warehouse?
Yes — storing bullion under bond in many jurisdictions defers VAT/GST until the metal is removed for consumption or local sale. Whether it avoids VAT entirely depends on the intended use (re‑export vs domestic sale) and local customs rules. Verify with customs and get written confirmation from the bonded warehouse and from your tax adviser before relying on this treatment.
What should I do if I change tax residence?
Obtain a written exit opinion from tax counsel before you move. Changing residency can trigger deemed disposals, exit taxes, or require re‑registration of foreign holdings. An exit opinion explains whether you should repatriate, retain foreign custody, or restructure ownership to limit tax costs.
How often should I physically verify serial numbers?
At minimum, request an independent inventory reconciliation annually. For larger holdings or higher operational risk, schedule a physical verification every 2–3 years by an independent professional. Ensure the custodian’s audit reports are part of your yearly compliance review.
Final checklist — what to have in place before you transfer gold abroad
- Written tax opinion covering VAT/GST and reporting obligations for your residence
- Signed custody/bailment agreement and serialised vault receipt
- Insurance certificate showing coverage limits, exclusions and excesses (review policy wording)
- Documented shipping contract with specialist bullion carrier and sample airway bill
- Exit playbook: preferred buyers, repatriation route, timelines and customs broker contact
- Suc