Overview: This August 2026 update revises our June piece on Loomis as a vaulting partner for retail bullion buyers. It summarizes Loomis' role at a glance, explains what changed in mid‑2026 for insurance and custody practice, and gives a sharpened checklist and recommendations so retail investors can assess whether a Loomis‑backed custody route suits their needs today.
At a glance — key specs
- Service type: Third‑party vault operator and secure logistics provider (not a retail dealer or direct‑to‑consumer custodian)
- Common vault locations used by dealers: London, Zurich, New York, Singapore, Stockholm and other regional hubs depending on dealer contracts
- Storage models offered (via dealers/platforms): Fully segregated (bar‑level allocation), allocated (account‑level allocation), and pooled/omnibus—availability and labeling depend on contract
- Auditability: Periodic physical inventories, independent audits where negotiated; some platforms now publish attestations or reconciliation snapshots
- Insurance: In‑storage and in‑transit cover provided variably—policy wording, named insured(s) and sub‑limits remain contract details buyers must inspect
Background: who is Loomis and why it matters
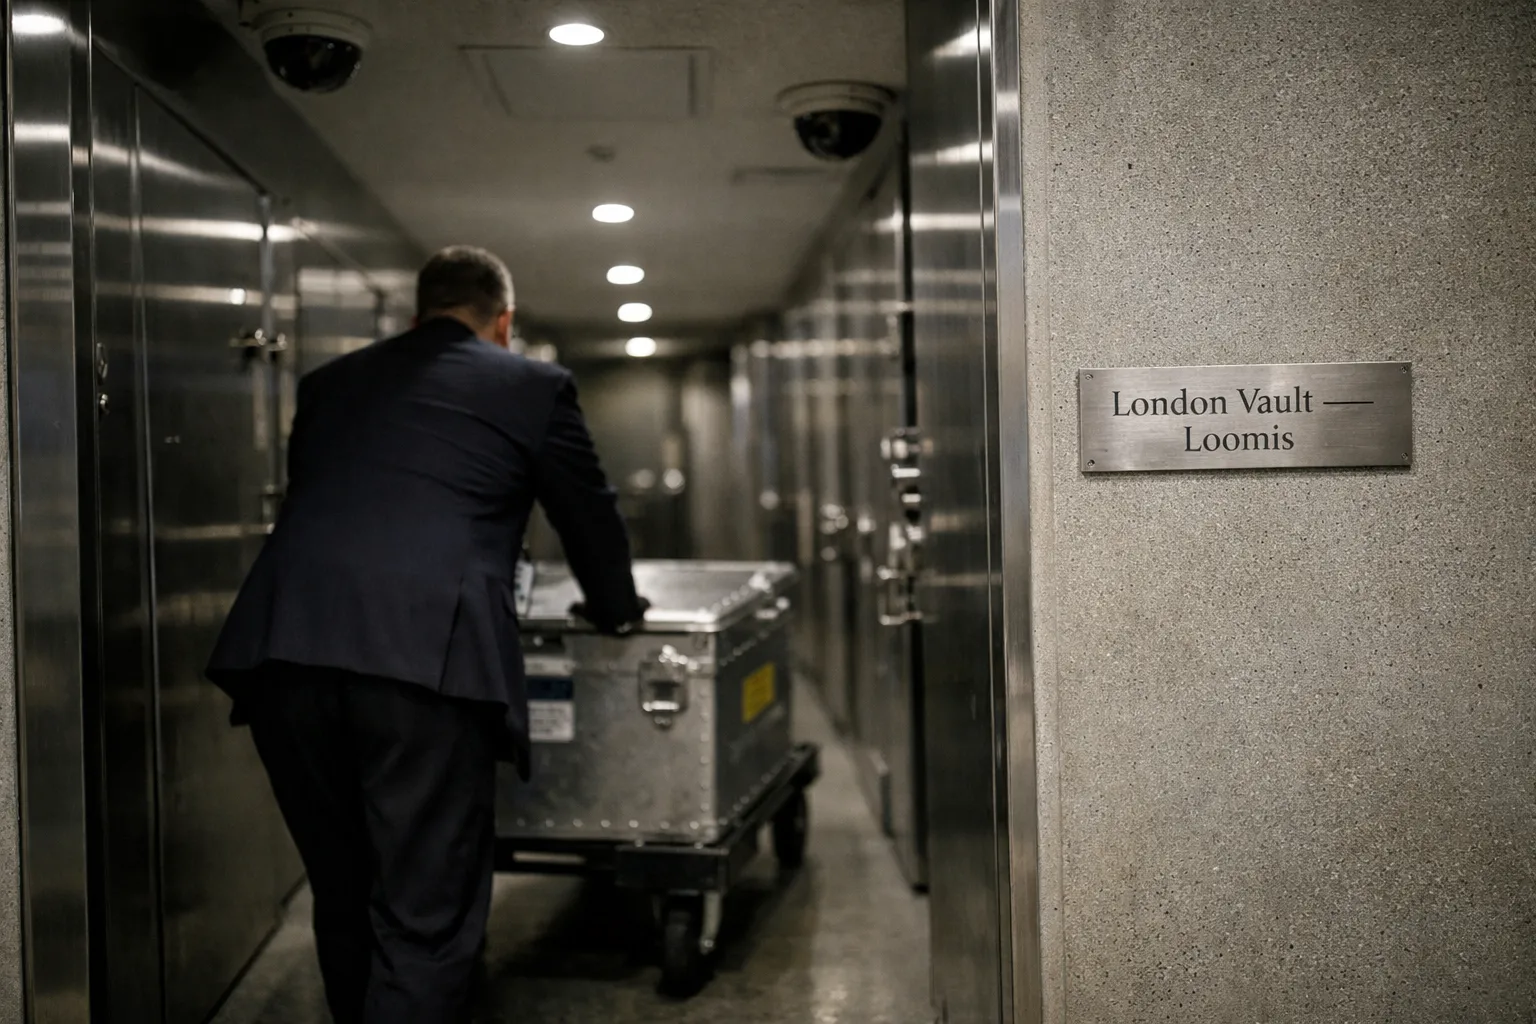
Loomis is a global vaulting and secure logistics operator relied on by bullion dealers, custody platforms and exchanges. It provides armored transport, vault storage and standardised chain‑of‑custody processes that most retail buyers cannot replicate. For dealers, using Loomis remains a cross‑market quality signal because it simplifies transfers between established bullion hubs and meets many insurer and market infrastructure expectations.
Features analysis — how Loomis works for retail buyers
Important framing: retail investors do not open accounts directly with Loomis. Dealers, exchanges and custody platforms contract Loomis to handle metal; your protections therefore flow from three linked documents: the vault operator’s operating agreement, the dealer/platform custody agreement, and the applicable insurance policy wording.
Operationally, Loomis provides:
- Networked vault and transport capability. Broad geographic coverage reduces single‑site concentration risk and facilitates cross‑hub transfers when dealers need to move inventory for liquidity or client delivery.
- Chain‑of‑custody controls. Barcode/serial tracking, tamper‑evident seals, controlled handoff procedures and documented receipts are standard practice in Loomis facilities.
- Support for segregation and pooled models. Loomis can operate fully segregated cages or bars and pooled/omnibus stores; which model you receive depends on contractual commitments from your dealer.
- Audit support. Facilities can accommodate independent auditors and provide inventory reports; an increasing number of dealers now request machine‑readable reconciliation files (CSV/API) for client statements.
What changed by August 2026 — why this update matters
- Insurance market continued to harden. Following underwriting pressure since 2023, underwriters have further narrowed territorial and peril coverage in 2026. Dealers we interviewed in July–August 2026 reported more frequent separate sub‑limits for transit, temporary storage and customs‑hold scenarios, and higher deductibles for non‑routine movements.
- More public transparency from major platforms. During 2026 an increasing number of custody platforms and dealers began publishing segregation status, named insurers and audit cadences on their public pages. This is not universal, but the trend accelerates—making transparency a differentiator when choosing a provider.
- Digital attestations and granular reporting. Platforms now commonly offer digital inventory reports and, in some cases, downloadable reconciliation files showing serials for segregated holdings. These tools make independent verification easier for retail clients.
- Fee‑structure tightening. To cover higher underwriting and logistics costs, several dealers adjusted minimums and movement fees in mid‑2026; small account holders reported higher per‑movement costs than in early 2026 when requesting delivery.
What Loomis does well (pros)
- Scale and multi‑hub redundancy. Loomis' network reduces concentration risk and supports inter‑dealer settlement.
- Established logistics practices. Experienced bullion handling and armored transport lower operational settlement risk compared with ad‑hoc local arrangements.
- Compatibility with market infrastructure. Holdings routed through Loomis typically clear market flows more smoothly—important if you plan to sell through major dealers or exchanges.
- Supports independent auditability. Loomis facilities accommodate external auditors and reconciliation protocols commonly requested by dealers and platforms.
Where Loomis can disappoint retail buyers (cons)
- No direct retail access. You cannot open a Loomis account—your terms derive from the dealer or custody platform contract.
- Fee and insurance opacity. Dealers still too often bundle storage, admin and insurance with differing disclosure. Allocated storage costs commonly range (across hubs and providers) between roughly 0.15% and 0.45% annually in 2026, with minimum fees frequently from $50 up to $250/year depending on provider and account size—always ask for a worked example.
- Insurance wording varies materially. Whether Loomis is a named insured, an additional insured, or merely a service provider affects recovery paths. Sub‑limits and exclusions (e.g., customs delays, war, cyber, or extreme events) are common and meaningful.
- Segregation status matters legally. Allocated‑but‑not‑segregated or omnibus models can change the practical priority of claims in insolvency or loss; that legal detail is set by your dealer’s custody terms.
Pricing and value — what to expect in August 2026
Storage costs and ancillary fees determine value. Current practical guidance:
- Allocated storage: Expect typical ranges roughly 0.15%–0.45% annually in major hubs. Institutional balances may secure lower percentage rates but negotiate minimums.
- Minimums and flat fees: Annual minimums commonly fall between $50 and $250. Some providers add fixed per‑movement fees for transfers or physical delivery that can exceed a year of storage for small accounts.
- Delivery/transfer charges: Cross‑vault transfers, assay fees, melting or custom packaging often carry separate charges—request a sample invoice for a 1 kg or 10 oz withdrawal to compare total cost scenarios.
Value judgment: Loomis‑backed custody generally makes sense if you prioritize professional chain‑of‑custody, multi‑jurisdictional settlement capability and audit‑ready custody. If your priority is the absolute lowest recurring cost and immediate physical access, a local vault or home storage will often be cheaper but trade off settlement and audit features.
Who should consider Loomis‑backed storage?
- Buy‑and‑hold retail investors who prioritise secure custody, documented audit trails and smoother resale settlement.
- Platform operators, portfolio managers and active traders who require interoperability across dealers and exchanges.
- Investors insisting on named‑insurer schedules, explicit segregation clauses and periodic independent audits.
Not ideal for collectors wanting daily physical access or micro‑accounts where minimums and per‑movement charges make custody uneconomic.
Alternatives — comparable vault operators
- Brink’s. Large global player offering vaulting and integrated logistics; comparable in scale and market interoperability to Loomis.
- Malca‑Amit. Specialist in high‑value logistics with strengths in Dubai, Geneva and key trading hubs.
- Prosegur. Global vault and security operator that competes on bespoke custody solutions and integrated transport services.
When comparing, prioritise contract terms (segregation language), named insurers, audit cadences and explicit per‑movement pricing rather than brand alone.
Practical checklist — what to ask your dealer now (August 2026)
- Is my bullion stored segregated (bar‑level allocation), allocated‑but‑not‑segregated, or pooled/omnibus? Request the exact contract clause and a sample statement showing serials for segregated bars.
- Which legal entity is the contractual custodian? Is Loomis the contractual custodian or a sub‑contracted vault operator? Ask for the vault operator’s full legal name used in your agreement.
- Who is the named insurer and can I review the insurance schedule or policy wording? Specifically ask for sub‑limits for in‑transit, ingress/egress, and temporary/customs storage, and the deductible amounts.
- How often are physical inventories audited, who conducts the audits, and can I see the most recent audit or reconciliation? Request machine‑readable reconciliation files where available.
- What are all fees (storage %, minimums, transfer/delivery charges, assay/minting fees)? Ask for a worked example: total charges to withdraw 1 kg, 10 oz, and a cross‑hub transfer.
- Are there policy exclusions (war, cyber, customs, or sovereign seizure) that could affect recovery? Confirm how claims are handled and who receives payouts in a loss scenario.
- In dealer or vault insolvency, are holdings held in trust or recorded as creditor claims? Ask for legal opinion or trustee structure that establishes client priority.
Verdict
Loomis remains a credible and operationally robust vaulting partner in August 2026. Its networked vaults, logistics expertise and audit‑friendly operations remain meaningful advantages for retail investors who access custody through reputable dealers or platforms. But Loomis is only one part of the custody equation—your dealer’s contract wording, named insurer and fee schedule determine your actual protection.
Bottom line: treat Loomis involvement as a useful baseline quality signal. Do not stop there—insist on named insurers, clear segregation clauses, published audit cadences and worked fee examples. If a dealer or platform refuses to provide those, consider alternatives or move to a provider that publishes contract terms and reconciliation reports.
Can I open a storage account directly with Loomis?
No. Loomis provides vaulting and secure logistics to dealers and platforms. Retail access comes through your dealer or custody platform contract; your legal and insurance protections derive from those agreements.
Does Loomis’ involvement guarantee full insurance coverage?
No. Loomis facilities typically meet insurer requirements, but insurance coverage is arranged by the dealer, the vault operator or jointly. Policies commonly include sub‑limits for transit and temporary storage, and exclusions that materially affect recovery—insist on seeing named‑insurer schedules and policy wording.
How can I verify my holdings if my dealer uses Loomis?
Request inventory reconciliation reports, independent audit reports and, for segregated holdings, serial numbers. Increasingly, dealers provide downloadable reconciliation files or digital attestations—use those to independently reconcile your account.
What should small account holders watch for in 2026?
Watch minimum fees, per‑movement charges and insurance sub‑limits. For small balances, movement or delivery fees can exceed annual storage costs. Ask for worked examples for withdrawals before committing.
Disclosure: This article is informational and does not constitute investment or legal advice. Investors should consult their dealer, a qualified attorney and, where appropriate, a tax advisor before making custody decisions.